OE Logo

In 2020, electricity represents around 21% of global industrial energy consumption. By 2050, this reaches 65% in our Net Zero Transition scenario.

Demand for capital goods will benefit from the large-scale investments required for countries to achieve Net Zero.

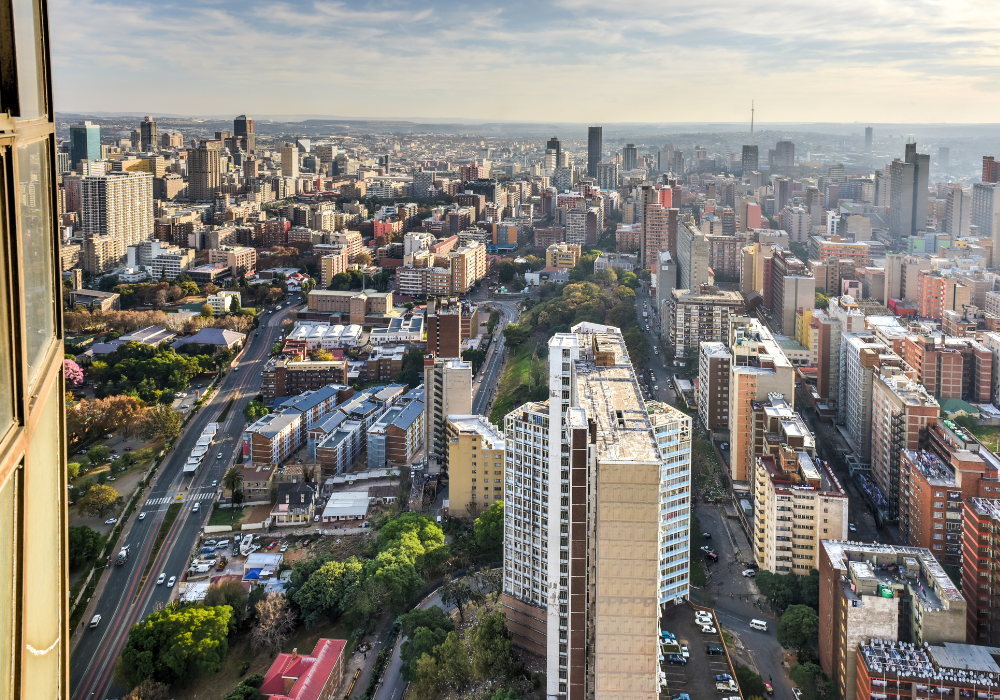
Johannesburg, South Africa

From economy to politics, investment to operation, fuel your business growth by leveraging our complete Africa solutions.

A woman wearing mask to protect herself from Covid

While China’s sooner-than-expected reopening has led some to pencil in a more robust rebound in 2023, we are more cautious. Our 4.5% growth forecast for 2023 remains below consensus.

Office building in London

Looking into 2023, real estate developers and investors will continue facing multiple pressures. The months ahead will see difficult discussions being made around which developments should still go ahead in 2023.

We believe 2023 is likely to be a difficult year for nearly all Asian economies. Growth should slow everywhere, except perhaps China and Thailand. The slowdown will likely be driven by a recession in the global economy but also due a shift global demand away from goods and towards services.

Indonesia parliament complex building

We expect Indonesia’s budget balance to show a large deficit in H2 of this year as the cost of fuel subsidies is finally reflected in the fiscal accounts.

Shipping port in Thailand, Asia

Manufacturing hubs in South East Asia are set to benefit from firms hedging against ongoing US-China frictions, in our view, and ASEAN countries will continue to be attractive destinations for investment.

Portrait of Benjamin Frankilin close-up shots from one hundred dollars banknote

The real-wages squeeze, slowing retail sales, and falling commodity and producer prices all point to inflation slowing down, albeit slowly. The real threat to fighting inflation now is a mis-calibrated fiscal support.

Reserve Bank of India, 2000 ruppes
Research Briefing | Sep 16, 2022

The terminal policy rate is in sight for India

Recent developments strengthen our view that India’s inflation has passed its peak. The steep rise in headline CPI that began in late 2021 was largely driven by imported inflation due to supply chain issues and sky rocketing commodity prices following Russia’s invasion of Ukraine. These pressures are now retreating.
Read more

Research Briefing | Sep 16, 2022

The terminal policy rate is in sight for India

Recent developments strengthen our view that India’s inflation has passed its peak. The steep rise in headline CPI that began in late 2021 was largely driven by imported inflation due to supply chain issues and sky rocketing commodity prices following Russia’s invasion of Ukraine. These pressures are now retreating.

Read more

Asia currency
Research Briefing | Sep 16, 2022

APAC central banks look to anchor expectations rather than follow Fed

Bank Indonesia finally raised its policy rate late last month, and a few weeks later Bank Negara followed with its third increase since May. The central banks of South Korea, India, and the Philippines have been increasing the policy rate for some time now. So, considering the economic conditions and the various challenges that central banks are currently facing, what is the likely outlook on interest rates?

Read more

Research Briefing | Sep 16, 2022

APAC central banks look to anchor expectations rather than follow Fed

Bank Indonesia finally raised its policy rate late last month, and a few weeks later Bank Negara followed with its third increase since May. The central banks of South Korea, India, and the Philippines have been increasing the policy rate for some time now. So, considering the economic conditions and the various challenges that central banks are currently facing, what is the likely outlook on interest rates?

Read more

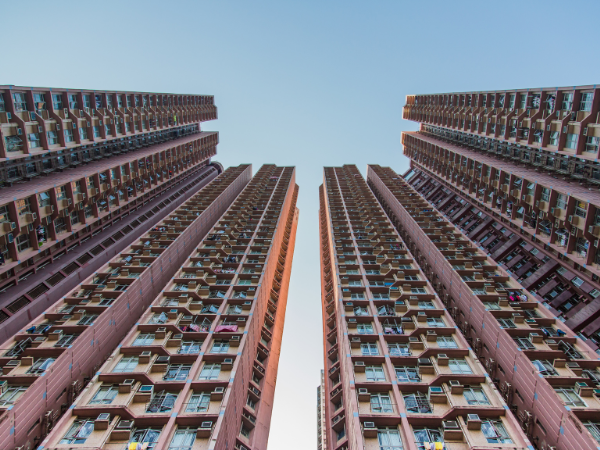
Hong Kong housing
Research Briefing | Aug 18, 2022

Hong Kong’s weak housing market to only get a reprieve in 2023

Hong Kong’s housing market sentiment weakened during H1 2022, reflecting a resurgence of Covid infections in Q1 and a weak domestic economic outlook. House prices in the secondary market fell 2.8% in Q2 versus Q4 2021. And this housing market weakness may not be over yet.

What you will learn:

  • As an international trade and financial centre in Asia, changes in Hong Kong’s external environment have an
    outsized impact on its domestic economy, and hence on its housing market.
  • We expect residential property prices to fall by about 4% y/y in Q4 2022, mainly due to the gloomy economic outlook. Slow border reopening progress and challenges to the external environment have severely dampened local sentiment.
  • Higher mortgage rates will also play a role in deterring lower income households from buying property and weigh on residential property investment demand.

Read more

Research Briefing | Aug 18, 2022

Hong Kong’s weak housing market to only get a reprieve in 2023

Hong Kong’s housing market sentiment weakened during H1 2022, reflecting a resurgence of Covid infections in Q1 and a weak domestic economic outlook. House prices in the secondary market fell 2.8% in Q2 versus Q4 2021. And this housing market weakness may not be over yet.

What you will learn:

  • As an international trade and financial centre in Asia, changes in Hong Kong’s external environment have an
    outsized impact on its domestic economy, and hence on its housing market.
  • We expect residential property prices to fall by about 4% y/y in Q4 2022, mainly due to the gloomy economic outlook. Slow border reopening progress and challenges to the external environment have severely dampened local sentiment.
  • Higher mortgage rates will also play a role in deterring lower income households from buying property and weigh on residential property investment demand.

Read more

Asian food

It is no secret that Covid-19 has disproportionately impacted women’s lives and their economic opportunities. As governments focus on stimulating economic recovery, they must now prioritise measures that help women. Indeed, McKinsey & Co has estimated that adopting gender-specific policies now could add $13 trillion to global GDP by 2030 compared to a loss of $1 trillion if countries choose gender-regressive recovery plans.

supply chain
Research Briefing | Aug 10, 2022

Improving supply chain conditions kick off H2 in the US

Supply-chain conditions in the US offered encouraging signs to start Q3, according to our supply chain tracker. Inflationary pressures ebbed and logistics challenges eased. Labor market dynamics improved while inventories maintained their ascent. Cooler activity resulted in a healthier balance between demand and supply.

Read more

Research Briefing | Aug 10, 2022

Improving supply chain conditions kick off H2 in the US

Supply-chain conditions in the US offered encouraging signs to start Q3, according to our supply chain tracker. Inflationary pressures ebbed and logistics challenges eased. Labor market dynamics improved while inventories maintained their ascent. Cooler activity resulted in a healthier balance between demand and supply.

Read more

A Chinese lady pulling up her mask to protect herself from COVID

We have cut our China growth forecast to 3.2% in 2022, from 4% previously, reflecting dismal Q2 growth and the absence of new stimulus. The bigger issue, however, is China’s dynamic zero-Covid policy, which, as long as it persists, seems likely to crimp private-sector growth.

APAC consumption

With most of the continent finally treating Covid as endemic, we expect APAC’s private consumption
growth to remain resilient in 2023 and generally outperform other regions

City of London, UK

Consumer spending in 2022 is stronger in London than in other UK nations and regions, although most—if not all—of the gains occurred in the year’s first half.

San Jose California

With increased uncertainty on the horizon, we have reduced our forecasts for GDP for most US metros. However, all of the top 50 are expected to see positive 2022 GDP growth with the tech-heavy metros reaping the strongest growth led by San Jose, Seattle, San Francisco, New York, and Los Angeles.

Oxford Economics launches our Global Risk Service, a suite of data-driven and forward-looking tools that measure macro-economic and financial crises risks in 166 countries.

A pen on newspaper which reads emerging market
Research Briefing | Jun 28, 2022

Where bank-sovereign embraces could turn poisonous

We use our sovereign risk tool (SRT) and our new banking sector risk tool (BSRT) to identify which economies are most vulnerable to a dual sovereign-banking crisis, and why.

In normal (and even slightly stressful) circumstances, the bank-sovereign embrace can stabilise the economic and financial system. However this embrace can become poisonous. History is littered with the carcasses of banks and sovereigns that dragged each other down as finance dried up.

Read more

Research Briefing | Jun 28, 2022

Where bank-sovereign embraces could turn poisonous

We use our sovereign risk tool (SRT) and our new banking sector risk tool (BSRT) to identify which economies are most vulnerable to a dual sovereign-banking crisis, and why.

In normal (and even slightly stressful) circumstances, the bank-sovereign embrace can stabilise the economic and financial system. However this embrace can become poisonous. History is littered with the carcasses of banks and sovereigns that dragged each other down as finance dried up.

Read more