World Economic Prospects
Each month Oxford Economics’ team of 450 economists updates our baseline forecast for 200 countries using our Global Economic Model, the only fully integrated economic forecasting framework of its kind. Below is a summary of our analysis on the latest economic developments, and headline forecasts. To access the full report (and much more), request a free trial today.
Request a free trial
High oil price and hawkish central banks add to 2027 growth challenges
- Since the start of September, we’ve lowered our world GDP growth forecast by 0.1ppt to 2.8%, leaving it at the bottom end of the tight 2.8%-3% range seen in recent years. The oil supply shock shows no sign of ending despite the rise in oil exports from the Middle East, making it harder for central banks to look through it. We therefore expect major central banks will raise rates further.
- Iran hasn’t been able to stop oil shipments through the Strait of Hormuz, but it has become significantly more costly to do so. and has significantly reduced shipments of more flammable refined oil products such as diesel, exacerbating supply chain pressures stemming from Russia.
- We don’t think a resolution to the Middle East conflict is likely anytime soon and expect the oil price will remain above US$100 per barrel for the next six months. However, diesel will be consistent with notably higher oil prices thanks to high crack spreads, and this will also be the case for other refined oil products.
- The upward revisions to CPI inflation will crimp consumer spending growth, but perhaps the bigger impact of higher-for-longer inflation will be on interest rates. The receding prospect of an imminent and sustained easing of the price of oil and its derivatives raise the risk of triggering a broader rise in inflation.
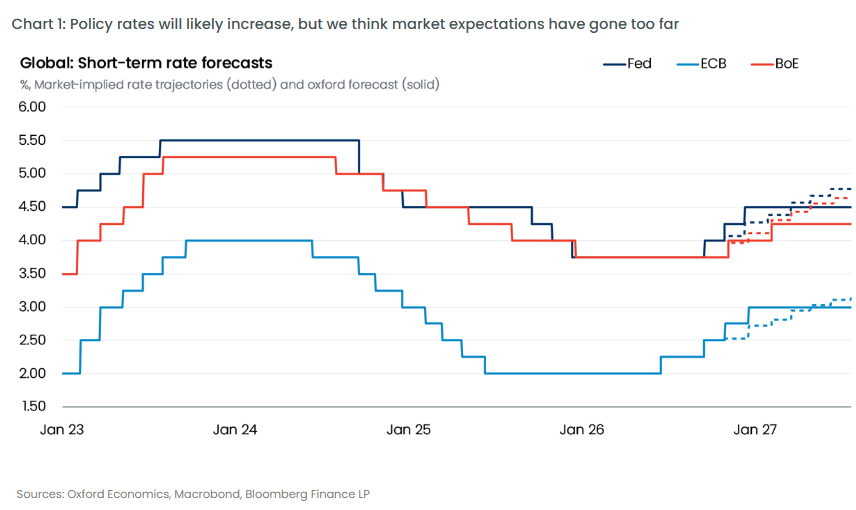
- The sustained oil supply shock coupled with the long period of above-target core inflation has pushed central banks towards hiking rates. We expect two further 25bps rate hikes by the Federal Reserve and European Central Bank, but we estimate fewer hikes than markets expect.
- The prospect of more rate hikes has contributed to the increase in long-term bond yields. The further rise in yields is also consistent with our long-held view that structural issues such as higher inflation uncertainty and greater government bond issuance point toward an era of high interest rates ahead.
Request a Free Trial
Complete the form below and we will contact you to set up your free trial. Please note that trials are only available for qualified users.
We are committed to protecting your right to privacy and ensuring the privacy and security of your personal information. We will not share your personal information with other individuals or organisations without your permission.
Find out how Oxford Economics can help you
Talk to us