

Inflation has fallen sharply in advanced economies over the past year, and we expect central banks to start cutting interest rates in the coming months. Commodity prices have reacted bullishly to every dovish signal by central bankers.
 Saarah Ghazi
Inflation has fallen sharply in advanced economies over the past year, and we expect central banks to start cutting interest rates in the coming months. Commodity prices have reacted bullishly to every dovish signal by central bankers.
On the surface, January’s headline jobs figures paint a healthy picture of the Canadian labour market, but a closer look suggests that things are not so rosy. Recent job gains have been mostly public-sector and part-time positions amid growing evidence of rapidly cooling hiring by businesses.
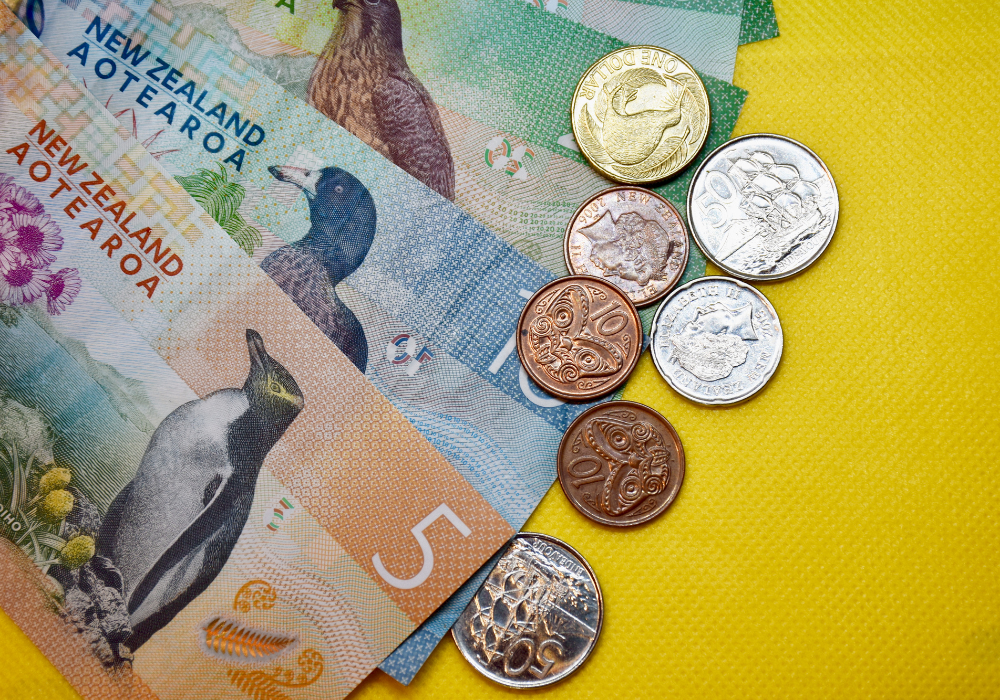
We remain steadfast on our long-standing heavy overweight in New Zealand government bonds within our global DM fixed income allocations.
According to findings from Tourism Economics’ latest Travel Industry Monitor (TIM), which tracks the views of tourism professionals every quarter, leisure tourism is expected to continue to spearhead travel global travel growth in 2024, especially for domestic and short-haul destinations.
We see the current conjuncture as representing a sweet spot for emerging market assets as disinflation is secure, activity is turning up, valuations are generally attractive, and global financial conditions appear supportive. In this week’s Beyond the Headlines, join Gabriel Sterne, Head of Global Emerging Markets, highlight why long run views are particularly potent right now during the Inaugural Global Economic Outlook Conference in London.
Emerging market (EM) central banks’ credibility to restrain inflation over the medium-term horizon remains intact despite the tests it’s been subjected to in an age of supply shocks and massive income disappointments – and despite name-calling by some banks’ political masters.
Our Cross Asset framework has improved in January and now signals an overweight stance on risk assets vs safe assets. In this week’s Beyond the Headlines, Javier Corominas, Director of Global Macro Strategy, breaks down our Global Asset Allocation for 2024 at the Inaugural Global Economic Outlook Conference in London.
In the last few years issues such as the cost of living crisis, and the Covid-19 pandemic have pushed the nature of the relationship between companies and their employees, communities, and wider political context to the top of boardrooms’ agenda.
We remain modestly risk-on as our above-consensus view on US growth this year still favours risk assets over bonds.
History suggests that presidential elections are not a significant driver of asset returns. That is, asset returns around elections are, on average, the same as returns outside of election windows. We expect this year to be no different.
Presidential elections not only have major implications for the future path of fiscal policy and the macroeconomic outlook, but they also impact the economy during the election year itself, albeit modestly. Elections create uncertainty around fiscal policymaking – our analysis suggests the most significant, negative impact occurs in Q4 of the preceding year.
The latest results point to a broad-based decline in US profit margins in Q4, reversing a recovery in Q3. We think margins will remain under pressure this year, resulting in further EPS disappointment despite an economic soft landing and limiting the upside for equities.
Over the last year, inflation has come down as we expected with the economy holding up relatively better in the second half of the year. In this week’s Beyond the Headlines, Innes McFee, Chief Global Economist, explains how the outlook for the year is cautiously optimistic during the Inaugural Global Economic Outlook Conference.
In our view, the Canadian economy has slipped into a moderate recession that will create slack, ease price pressures, and bring headline CPI inflation back to the 2% target by late 2024. In this month’s Canada Up Close, join Cassidy Rheaume, Associate Economist, as she discusses the outlook for inflation in Canada
Florida’s economic prospects remain strong. Its wider attractions for people and business have encouraged in-migration but also put pressure on housing affordability, particularly in Miami. Tourism remains an important sector, but some metros will benefit from growth in finance, government, and wholesale trade. The Villages and Naples will see strong job growth.
Our expectation for the US industrial sector to outperform other major commercial real estate sectors is predicated on the persistence of e-commerce sales growth supporting US warehouse demand. Over the next five years, we predict industrial total returns will average 6.9% per year, compared to all-property returns of 6.4%.
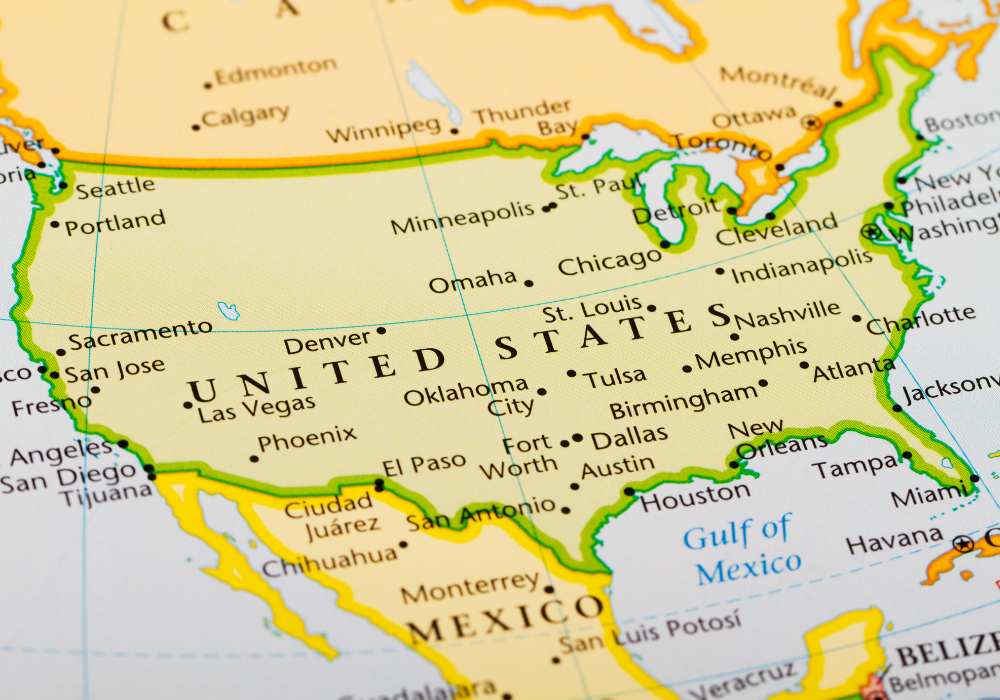
Under our latest climate scenario analysis, net zero policies in the US will have highly unequal impacts across states and metros, given the diverse nature of subnational economies. Places dependent on oil and gas activity will face the greatest challenges, followed by those with a greater reliance on manufacturing.

Join Sarah Nelson for an insightful exploration of the sustainability landscape in 2024. In this episode, she engages with leading experts in politics, technology, and sustainable business to unravel the key trends poised to shape our journey towards a greener future.
We move to a modest overweight on risk assets this month as we have become more optimistic on the global cycle. Our forecast for US growth this year is now clearly above consensus, and we see the risk balance for our China growth forecast as tilted to the upside.
Artificial Intelligence (AI) is shifting the impact of automation towards highly-skilled, intellectual occupations, meaning that cities that are highly reliant on those occupations are more likely to be exposed. However, these cities could in fact benefit from significant gains in productivity, further deepening the gap between successful cities and other places.