
Research Briefing
| Feb 27, 2024
Fixed Income: Kiwi bonds to fly high
We remain steadfast on our long-standing heavy overweight in New Zealand government bonds within our global DM fixed income allocations.
What you will learn:
- Upside surprises in activity and inflation this year have opened the market’s mind to the possibility of a hike in H1. But we doubt the criteria set out in the November monetary policy statement for a hike have been met.
- Our economists think the RBNZ will instead remain on hold in H1 before cutting twice in H2 as inflation falls to target and unemployment rises.
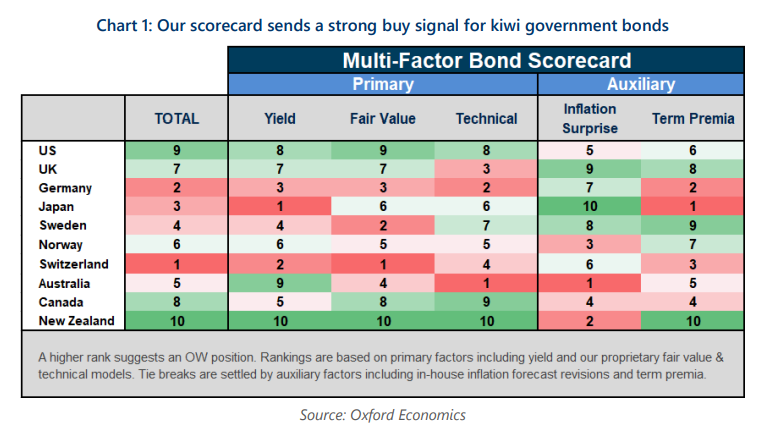
- Our multi-factor rates scorecard adds to our conviction, sending a near unanimous signal that kiwi bonds will outperform other developed market govies in the near term, based on attractive term premia, cheap valuations and strong mean-reverting properties.
Related Reports
Click here to subscribe to our asset management newsletter and get reports delivered directly to your mailbox
Why bond yields and term premia are likely to remain high
Term premia are now back to their mid-2000s levels – high compared to the last 10 years.
Read more: Why bond yields and term premia are likely to remain high
How will central banks react to higher bond yields?
We expect major central banks will continue to tighten in coming months.
Read more: How will central banks react to higher bond yields?
Bonds and the end of the global savings glut
Is the “end of the global savings glut” story reflected in bond prices? Three different approaches to fair value for 10-year Treasurys suggest the answer is yes.
Read more: Bonds and the end of the global savings glut
Economics for Asset Managers
Read more of our analysis and reports on asset management and economic outlook.
Read more: Economics for Asset Managers