OE Logo

The supply-shocks era represented the first time in a generation where inflation significantly eroded the real value of global public debt. For EMs, the erosion averaged 3.7% of GDP between 2020 and 2023; the average for advanced economies (AEs) was twice that (7.3% of GDP).
This year is set to be a turning point for commercial property markets in the US. A gradual easing in inflationary pressures alongside a steady, if unspectacular, year for GDP and employment growth should help to ease the market through the final leg of the post-COVID adjustment.

Despite the upgrade to our global economic outlook since December 2023, the Q1 update of our IFRS 9 and CECL scenarios services sees a more balanced assessment of the risks to the global economy over the next two years.

We expect the March employment report to show moderating job growth, adding to the Federal Reserve’s confidence that the labor market is rebalancing and that wage growth has slowed.

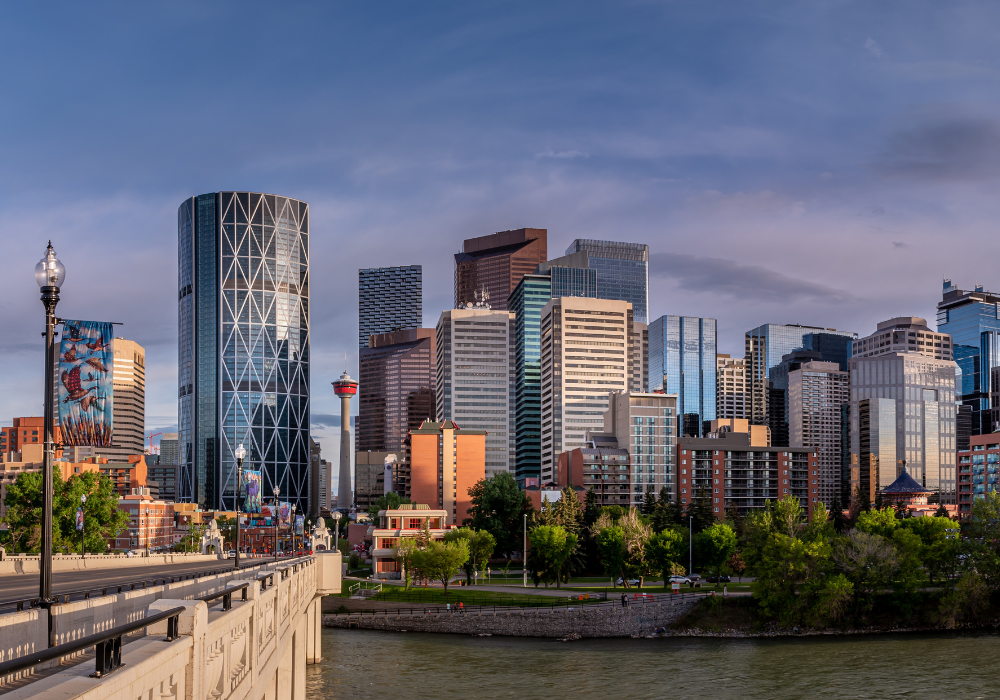
Overall, the medium-term outlook for Canadian metros is strong in terms of total GDP, with the country’s 10 major metros averaging 2.6% growth per year to 2028, outperforming the national average. However, five-year growth rates mask a more turbulent story in most metros.

We forecast stable GDP growth across most US metros in 2024, followed by decelerating growth over the subsequent four years. All of the top 50 metros are forecast to see real GDP growth in 2024 as well as continued but slower growth through 2028.

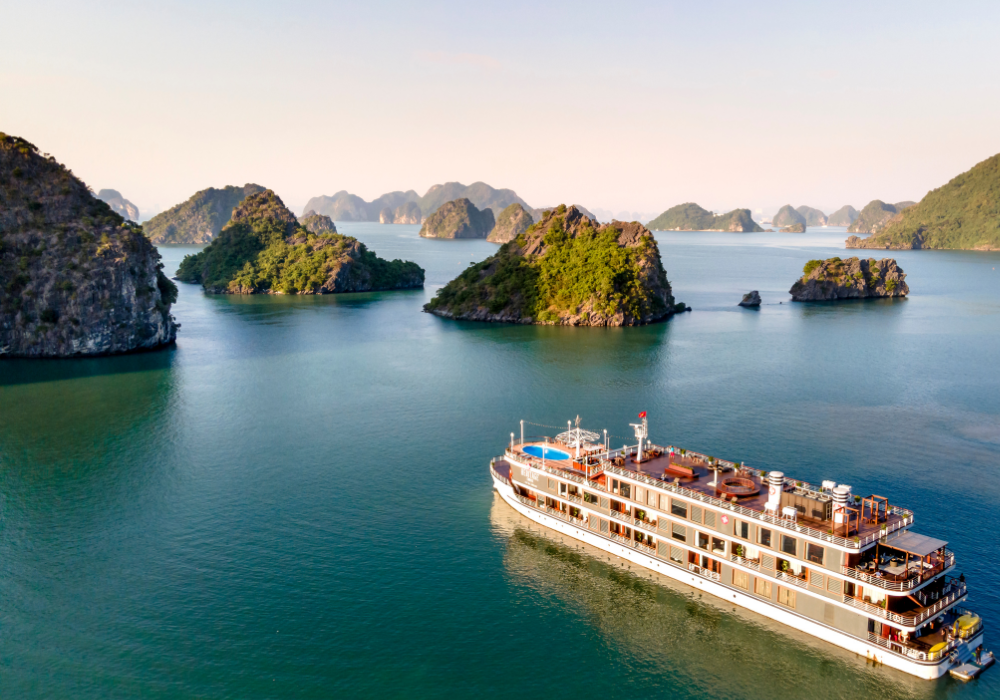
Based on research conducted in Q4 2023 among active cruisers from five key markets, consumers demonstrated a strong preference to undertake cruises within their own global region.

Our analysis of Banxico’s reaction function reaffirms our forecast that the policy rate will end the year at 8.25% – 1.25ppts lower than the consensus expectation of 9.50%. We expect larger rate cuts in Q4 2024, once inflation falls within the target range.

We think low quality stocks will be the key beneficiaries of our soft-landing view. In this week’s Beyond the Headlines, Javier Corominas, Director of Global Strategy suggests that these stocks have been the most vulnerable to rising bond yields over the past year but are likely to fare better as the major central banks begin to cut rates around the middle of the year.

Our business cycle indicator implies that the economy is losing momentum, but there are some caveats. Some of the data has been negatively affected by weather and aggressive seasonal adjustment factors, so could reflect noise rather than signal.

US business investment continues to advance, despite fears it would tumble in 2023 ahead of a widely anticipated recession.

We think lower quality stocks such as small caps will be the key beneficiaries of our soft-landing view. These stocks have been the most vulnerable to rising yields over the past year but are likely to fare better as the major central banks begin to cut rates around the middle of the year.

The West’s major central banks are well into their quantitative tightening programmes, reducing their combined balance sheet by $5.1 trillion. Central bank assets are still at extremely high levels though, resulting in excess liquidity in the banking system. This means QT can still hurt asset prices, even if these losses have been recuperated in recent rallies.

In February, Canada saw a solid advance in full-time employment, but these new positions were predominantly in the public sector for the third month in a row, while private-sector employment declined, after stagnating for two months. In this month’s Canada Up Close, join Callee Davis, Economist, as she discusses why Canada’s labour market is not as healthy as recent headline figures suggest.

In our March baseline we revised down substantially our long-term forecast for housing starts to better align it with our updated population projections. The new forecast is for housing starts to decline gradually to a 1.2mn seasonally adjusted annual rate by 2050, compared with 1.6mn in the February baseline.

The pandemic was associated in many minds with a flight of people away from city centers, raising doubts over the future trajectories of the four major East Coast metros in the US. Subsequently, New York City in particular faced various other challenges, including but not only the writers’ strike.

With a team of award-winning economists and proprietary forecasting models, Oxford Economics has been analysing and writing extensively about these market trends as well as their broader implications for asset allocation.

The gender pay gap in the UK has been gaining publicity in recent years, but progress to reduce it has been slow. For full-time employees, there has been a narrowing in median gross hourly earnings between men and women by 2.3 percentage points since 2013 and at the current rate of change, the gap won’t close until 2051.

Five manufacturing sectors have contributed significant job growth in many metros in recent years, at a time when employment in the broader sector has been largely stagnant: pharmaceuticals; computers and electronics; automobiles; aerospace; and food and beverage manufacturing.

Using alternative and proprietary data, Oxford Economics have developed a unique Multi-Factor Bond Scorecard to help Asset Managers identify more opportunities in fixed income markets. During a recent macro roundtable, Javier Corominas, Director of Global Macro Strategy, explained why his team were maintaining a heavy overweight on NZ Bonds.