


Over the medium and long term, differences in city economic performance are hugely influenced by disparities in productivity growth. In explaining past variations, national factors are important as are differences in industrial structure.
 Saarah Ghazi
Over the medium and long term, differences in city economic performance are hugely influenced by disparities in productivity growth. In explaining past variations, national factors are important as are differences in industrial structure.
The global economic outlook has deteriorated, with downside risks threatening global real estate.
We anticipate most advanced economies will fall into recession in 2023 and global growth will be weaker than the consensus expectation. In that context, we have identified three themes that we think will dominate the economic outlook and financial markets.
Following the conclusion of HomeBuilder, rising property prices and interest rate hikes, first home buyer (FHB) demand has normalised to its pre-pandemic base.
Many cities in the world’s advanced economies will enter recession in 2023, with soaring inflation and tightening monetary and fiscal policy driving down demand. In contrast, the majority of cities in emerging economies will still enjoy robust economic growth.
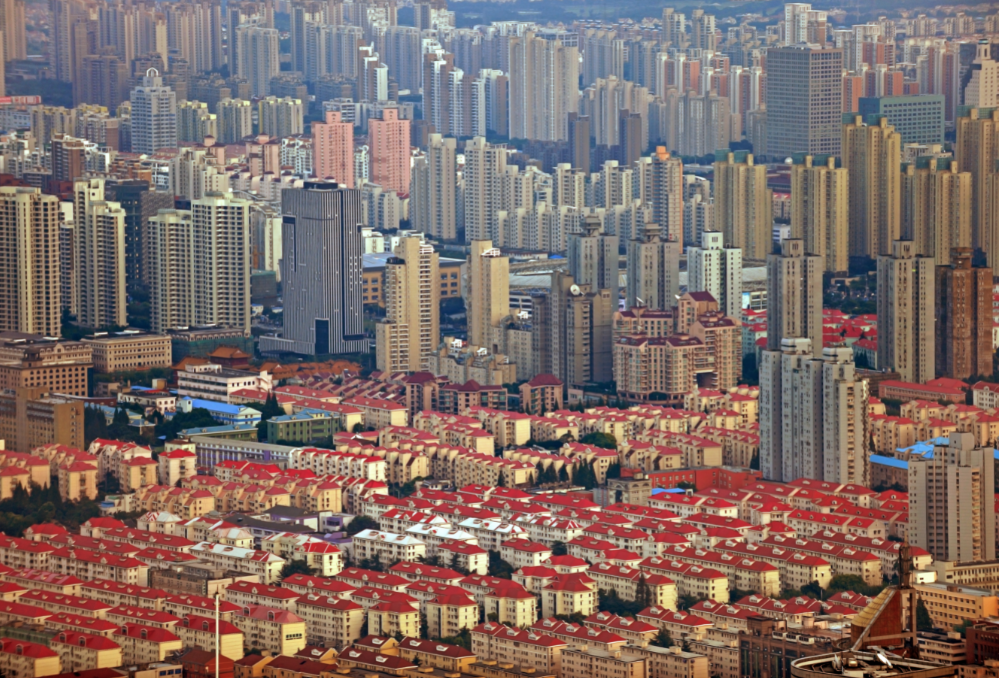
Policies aimed at managing China’s housing slump have led investors to query the shape and depth of a market correction. We think a meltdown is unlikely and that China’s housing market will instead undergo a protracted L-shaped downturn.
We think China’s exit from its zero-Covid policy will only happen in H2 2023 – a more cautious view than consensus. From an epidemiological and political perspective, we do not think the country is ready yet to open up.
While our outlook for emerging markets (EMs) is more upbeat than for advanced economies (AEs), we have cut our 2023 GDP growth forecast for EM ex-China by 0.3ppts to 2% due to rising global headwinds. Despite weaker growth, we’ve raised our inflation forecast 0.4ppts to 9.1%.
Policy divergence will continue to be a key theme in global FI markets in 2023. Whereas we pencil in a rate pause, rather than a pivot, in the US next year, the hiking cycle is still ongoing in Europe and will extend well into 2023, with considerable uncertainty as to the terminal rate.
The Hungarian economy is being hit by a perfect storm of shocks, particularly surging inflation and a weakening currency. Our baseline forecast already anticipates a recession over the winter and inflation staying elevated for some time.
How traditional enterprises can learn valuable lesson from digitally native organisations
The strength of the US labor market, as demonstrated by the increase in job openings in September, will frustrate the Federal Reserve and raises the risk of a policy mistake.
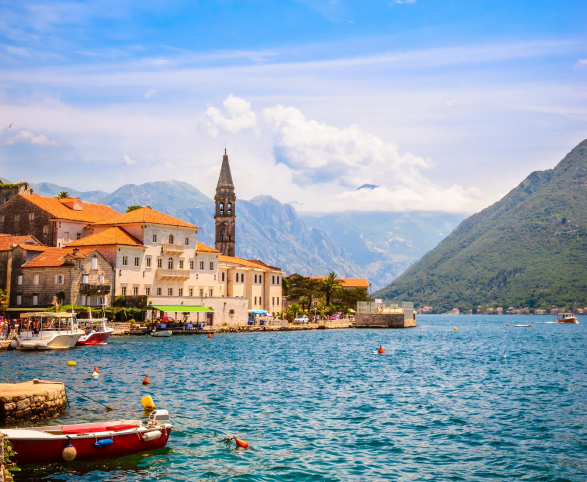
Europe enjoyed a strong tourism rebound over the summer months as Covid-19 disruptions abated. However, the region was not exempt from turmoil arising from the prolonged war in Ukraine, labour shortages, elevated food and energy prices, and stalling economic growth.
Looking into 2023, developers and investors have to assess conflicting pressures to construction costs, rising interest rates, and falling capital and income.
Supply chain developments were mixed in October, but the implications for the outlook, particularly for inflation, are modest. The easing of transportation stress helped push our supply-chain stress index lower, and a dip in price pressures helped drive the headline down.
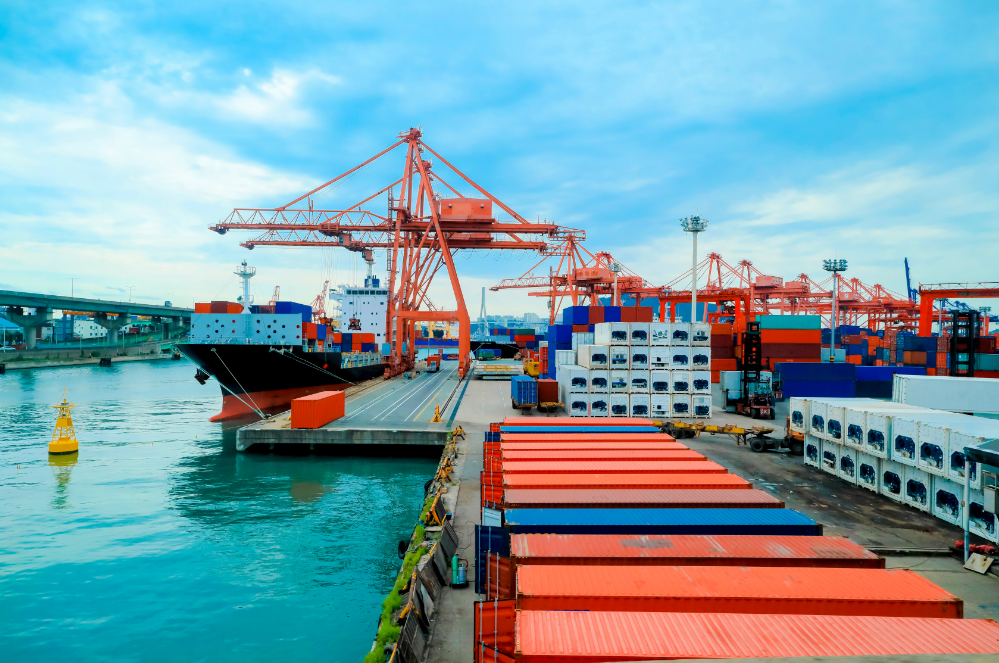
Timely October trade data from North Asia are flashing warning signs that Asia’s export downturn is gathering momentum. We think exports from elsewhere in Asia are likely to follow a similar trend, as they have in the past.
The National Bank of Poland (NBP) kept its policy rate unchanged at 6.75% at yesterday’s meeting, undershooting consensus and our expectation of a 25pbs hike.
Despite an upside growth surprise for Q3, we still expect the eurozone to fall into a widespread recession. Not all countries will be impacted uniformly, though – our new country-level indicators for Germany and Italy point to recession probabilities being significantly higher and the business cycle weakening more in these countries than in France and Spain.
A remarkably consistent fact of energy usage across economies, industries, and energy types is that intensity has come down steeply in recent decades. In other words, the amount of energy required to conduct a given amount of economic activity has fallen.
Despite the recent deterioration in the UK housing market, we think the doomsday scenario set out in the Bank of England’s latest banking stress test is extremely unlikely, based on our modelling.
