OE Logo

While most measures suggest a tight UK labour market, the pass-through to wage growth has been weak. We expect labour demand to soften in 2023, which should loosen conditions in the jobs market and encourage the MPC to take a less hawkish approach than markets anticipate.
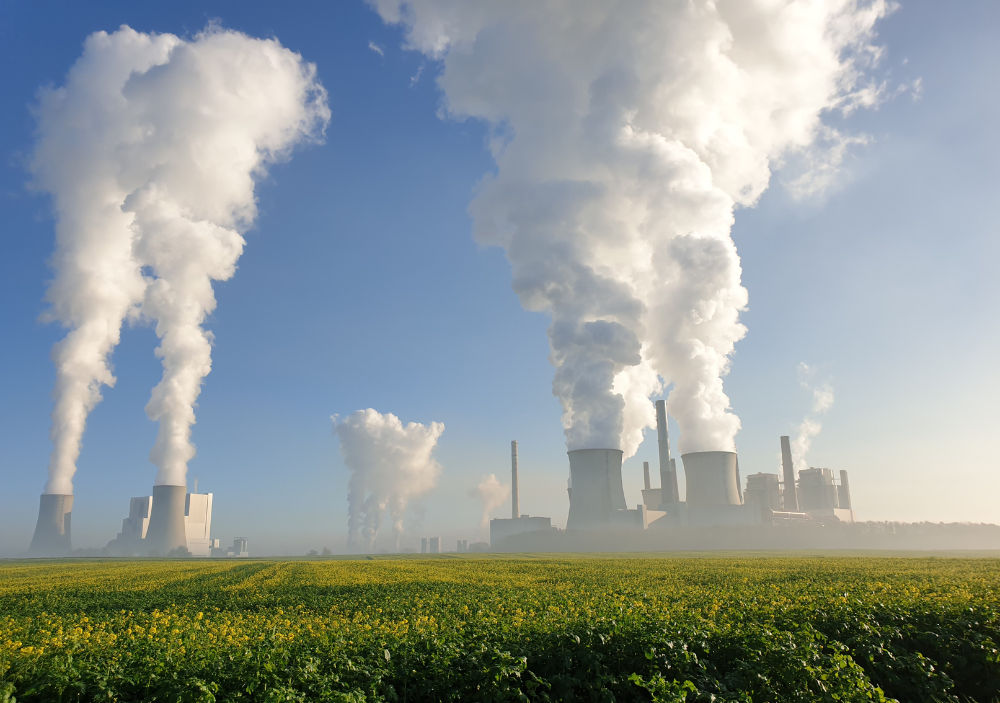
South Africa’s detailed JET IP unveiled at COP27 offers a model for other carbon-intensive developing countries to follow. Although the $8.5bn JETP pledge made at COP26 has a central catalytic role to attract more funding, the JET IP demonstrates that it is a far cry from the R1.5trn required in investment over the next five years alone.

The precipitous decline of the Yen to record fresh lows (and briefly above 150 last month) coupled with a dramatic surge in energy prices has resulted in above-target headline (2.9%) inflation, as well forty-year highs in survey-based inflation expectations.

Our analysis of the economies of metros across the US provides us with a basis for projecting household income growth and consumer spending patterns, both overall and by market segment.

The CNB again left the policy rate unchanged at 7% at the November meeting, staying put for the third consecutive time and matching our and consensus expectations.

Russia’s shutdown of natural gas flows to Europe has resulted in skyrocketing regional prices. This has contributed to a significant downgrade of our global and national economic growth forecasts and will impact European industry negatively.

The BoE raised Bank Rate by 75bps to 3% at its November meeting, in line with our expectations and market pricing. But the MPC sent a clear message that market pricing further out is too high.

Russia’s quick U-turn over its earlier decision to suspend participation in the Black Sea grain initiative suggests that pressure from emerging economies got the upper hand over Russia’s efforts to weaken Ukraine’s economy.

To no one’s surprise, the FOMC raised interest rates by 75bps for a fourth consecutive meeting, lifting the target range for the fed funds rate to 3.75% to 4.00%.

A review of the wider benefits that UK rail delivers for passengers, commuters, job-seekers, and the environment.

Our baseline forecast is for consumer spending in the eurozone to fall over the next two quarters as consumption fundamentals – real incomes and employment – weaken, while soaring energy prices keep inflation high.

Russia’s decision to halt its participation in the UN-brokered Black Sea grain deal risks a renewal of global food price pressures and could prove damaging to Ukraine’s agricultural output long term.

Qatar’s hosting of the Middle East’s first ever World Cup is seen benefitting the wider GCC economy, and given the recovery in travel and tourism, we forecast the region’s non-oil sector to grow by 4.9% and 3.4% in 2022 and 2023, respectively.

Since the invasion of Ukraine in late February, hundreds of thousands of Russians have fled to neighbouring countries to avoid the draft. The September mobilisation has added to that wave.

After a tighter-than-expected runoff on October 30, Lula da Silva (PT) was elected president of Brazil for a third time. He defeated the incumbent Jair Bolsonaro (PT) by just two million votes.

The state of the market for valves and actuators is often seen as a bellwether for the state of the industrial economy. Against that backdrop our latest forecasts contain some worrying signals.

International visits to Atlanta will grow 178.7% to 1.0 mn arrivals in 2022. This growth equates to an additional 648,000 arrivals compared to 2021.

UK government’s U-turns on tax cuts, the prospect of further fiscal policy tightening, and calmer financial markets mean the Monetary Policy Committee (MPC) faces less pressure to increase interest rates aggressively.

Central banks around the world are raising interest rates and shrinking balance sheets, but financial conditions are not under enough pressure to signal an oncoming crisis. We believe the global financial system still has ample liquidity lying dormant in reserves.

OTAs generate additional travel demand for accommodations in Europe boosting GDP and job creation. In particular independent accommodations benefit from OTAs by accruing a larger share of bookings than the market average. OTAs support more equitable development across Europe by orienting consumers towards rural areas.