

We expect the structural shift to working from home to continue to negatively impact the US office sector over the long term. Our capital value forecast for all US offices by the end of the decade is 17% below 2021 values.
 Saarah Ghazi
We expect the structural shift to working from home to continue to negatively impact the US office sector over the long term. Our capital value forecast for all US offices by the end of the decade is 17% below 2021 values.
Oxford Economics has introduced its new Tech Spend Monitor that provides forecasts of US spending on enterprise technology by industry.
Our comprehensive Impact Calculator (created by Oxford Economics economists) gauges the value geospatial services provide to organizations across different industries.
We receive many questions on the state of the US economy from clients. Here, we answer the top five most common, covering banking system stress, the impact of the looming recession, labor markets, inflation, and housing.
Supply chain stress eased further in March and we expect conditions to continue improving through the rest of 2023.
Providers of technology services benefitted from the coronavirus pandemic. Structural changes impacted virtually all industries worldwide, causing investment into the sector to heat up. As a result, employment within the sector grew significantly.
Oxford Economics is excited to announce the launch of our City Climate Scenario service, designed to help businesses and governments better understand the local impact of climate mitigation policies.
Using data from our new Industry Climate Service we examine the responses of the land transportation services sector to different climate change scenarios.
The recent banking sector turmoil could trigger a chain reaction of events that plunges the global economy into recession. However, we don’t think this is the most likely scenario.
Los Angeles benefited from a strong recovery in film sector and tourism-related jobs in 2022, finally yielding a recovery of lost pandemic jobs in Q1. Los Angeles’s net job change from Q1 2020 to Q1 2023 was 0.4%, still below the US net growth of 2.3%.
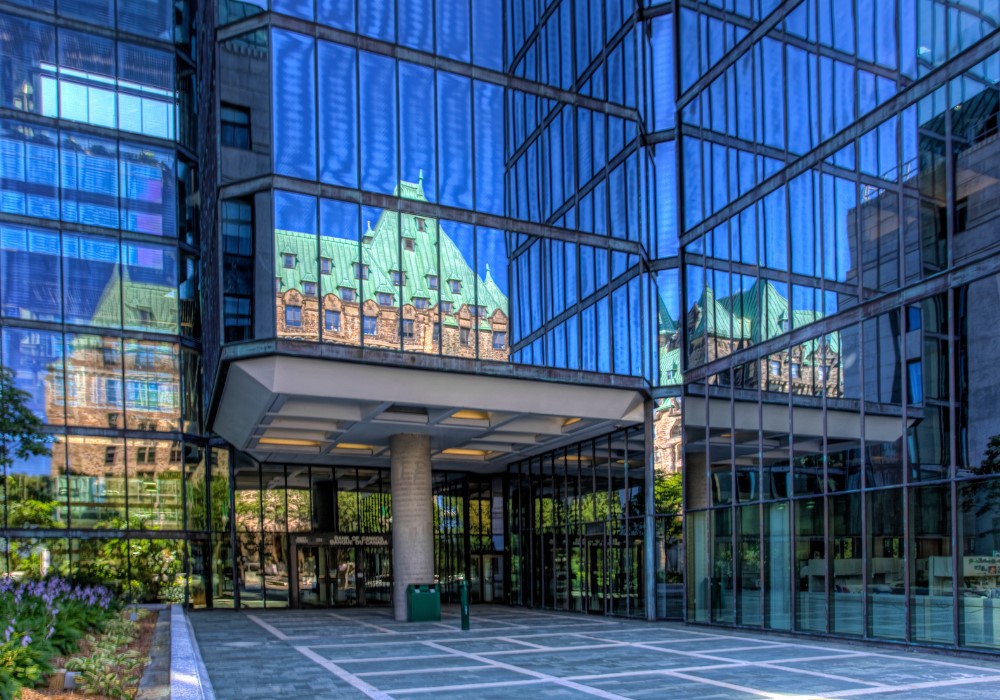
As expected, the Bank of Canada (BoC) held the target for the overnight rate steady at 4.5% in April and is continuing quantitative tightening.
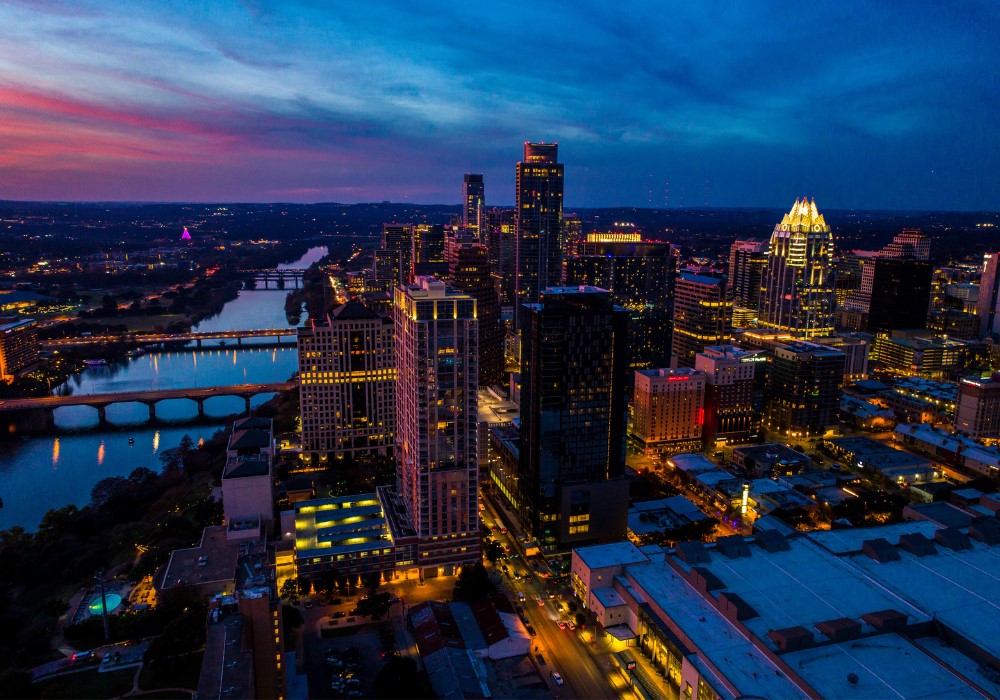
Austin’s large and expanding tech sector will escape many of the recessionary forces in the second half of 2023.
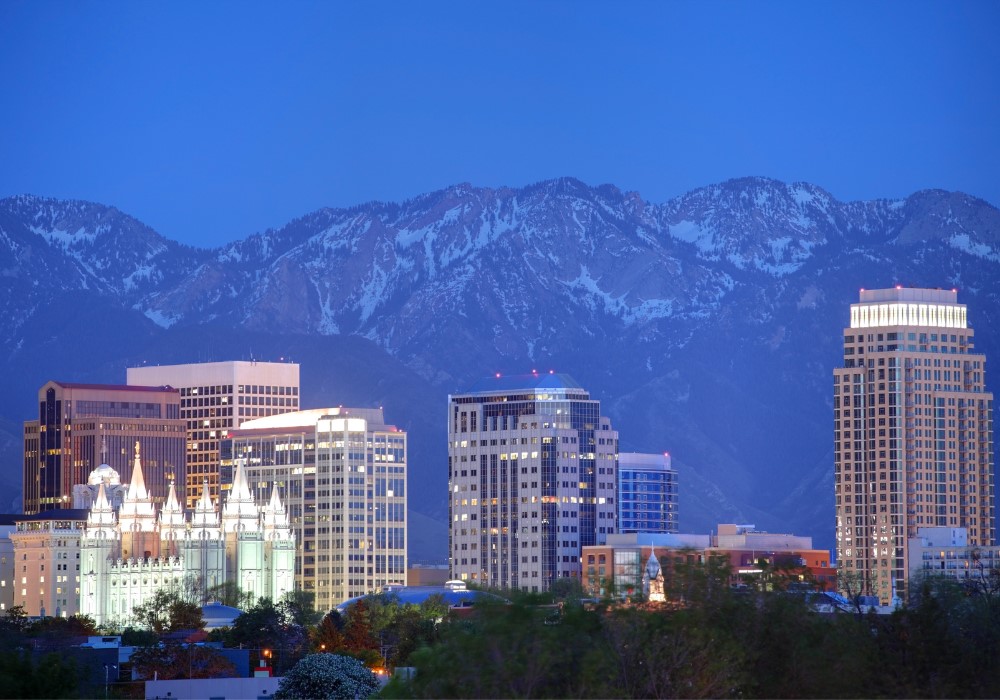
With healthy in-migration and a burgeoning tech sector, Salt Lake City was one of the first metros to recover from the pandemic. Its job growth rate decelerated in 2022, however, and is expected to continue to do so over the next few years.
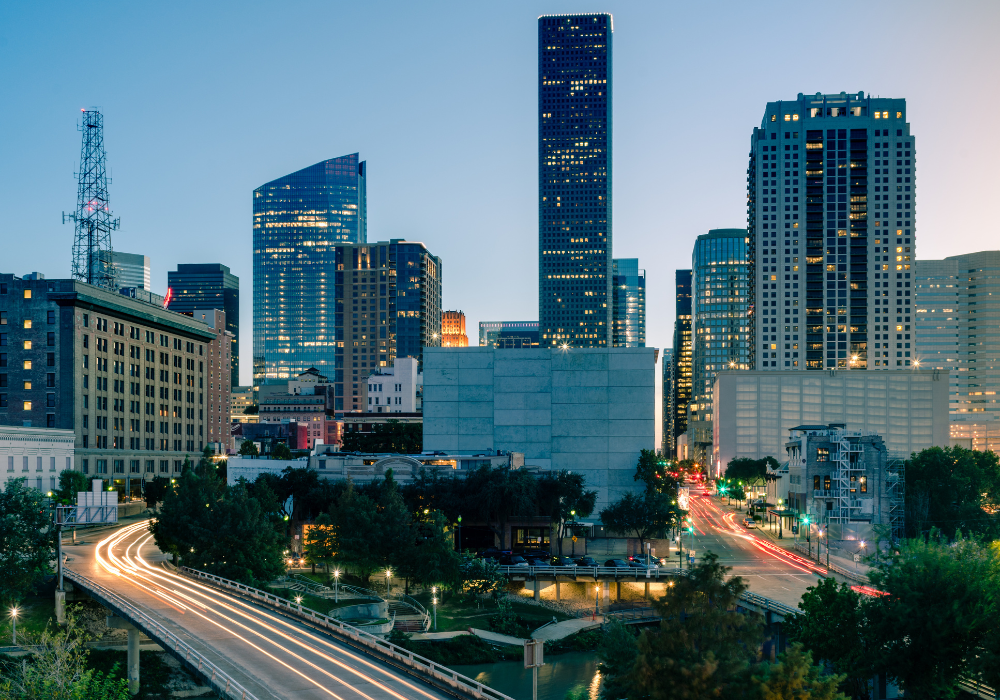
Houston’s economy will benefit from in-migration in 2023 and see moderate growth in a broad range of industries, but its pace of growth will continue to trail most of its Texas peer metros.
The IMF’s forecast still looks too optimistic over the next 2 years in our view. The impact of bank funding turmoil looks to have been offset in their forecasts by the positive developments in European energy markets, solid economic momentum and China’s earlier than expected reopening, to leave the IMF’s global GDP projection broadly unchanged.
Oxford Economics forecasts US business spending on enterprise technology will fall -1% in the second half of 2023, after rising over 10% on average during 2021-2022. Leading the downturn will be spending from the manufacturing, information, and financial sectors.
The sharp fall in our US business cycle indicator in February signalled the economy lost momentum midway through Q1.
In 2020, production of Season One of “Sweet Tooth” resulted in total spending in New Zealand of over NZ$46 million.
The IPCC’s synthesis report updates the latest science on climate change. The message is familiar: unless emissions are cut rapidly and deeply, adverse climate impacts will intensify.
There is a scramble for African critical minerals amid the ‘New Cold War’ brewing between the US and China.