
In this blog, we discuss the implications of the US–Venezuela conflict for both countries’ economies, as well as for global oil markets.


 Sally Li
In this blog, we discuss the implications of the US–Venezuela conflict for both countries’ economies, as well as for global oil markets.
Trade restrictions, increasing competition in higher value-added industries, and elevated AI investment will push cities onto different growth paths.
We forecast construction activity will rebound in 2026, underpinned by four key themes that will define the year.
Even under our strong upside scenarios for oil and migrant return, Venezuela’s GDP returns to just 50% below the 2013 peak in ten years.
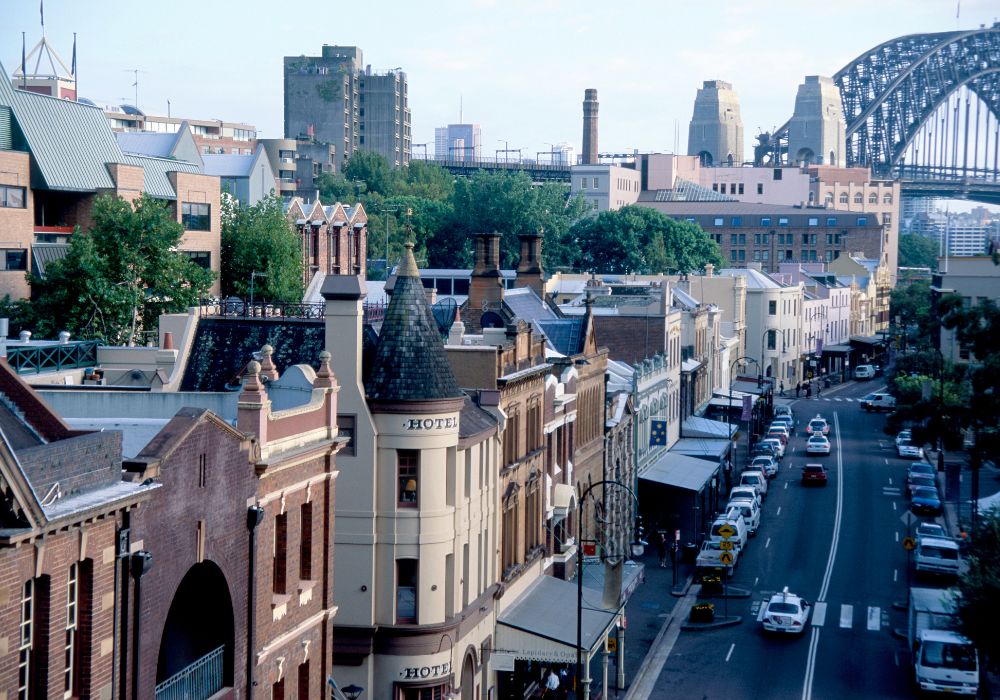
Australia faces a series of tussles for 2026 – inflation versus the RBA, public versus private demand and homeowners versus everyone else.
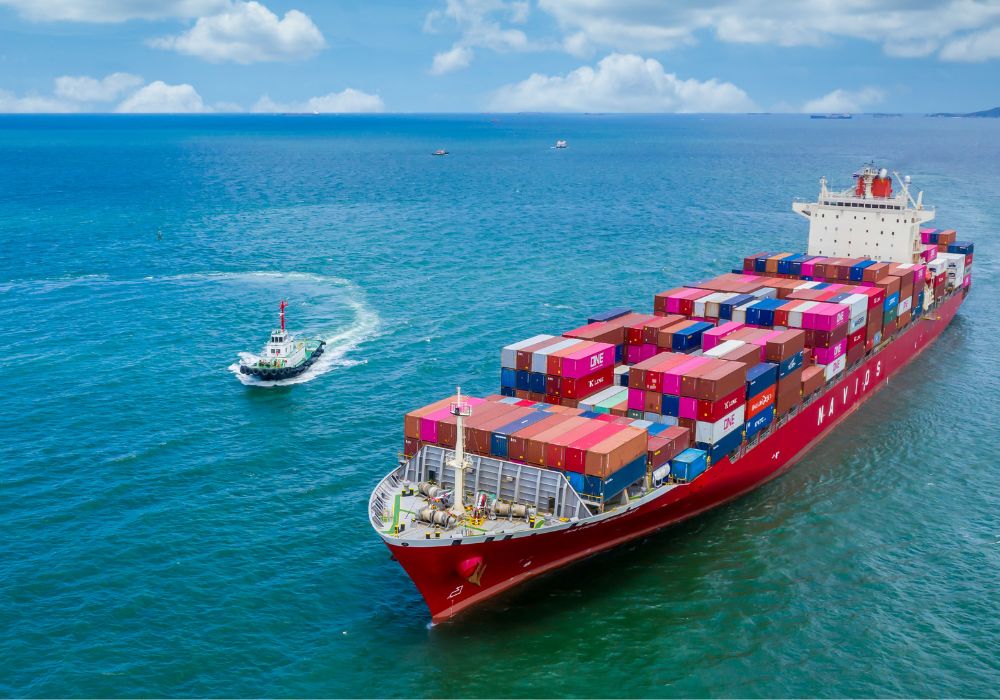
Global trade will be caught in a tug-of-war between tariffs and AI, capping growth at 1.2% in 2026.
Canada’s industrial property outlook for 2026 points to broad resilience. Explore which markets fare better and the key risks influencing performance.
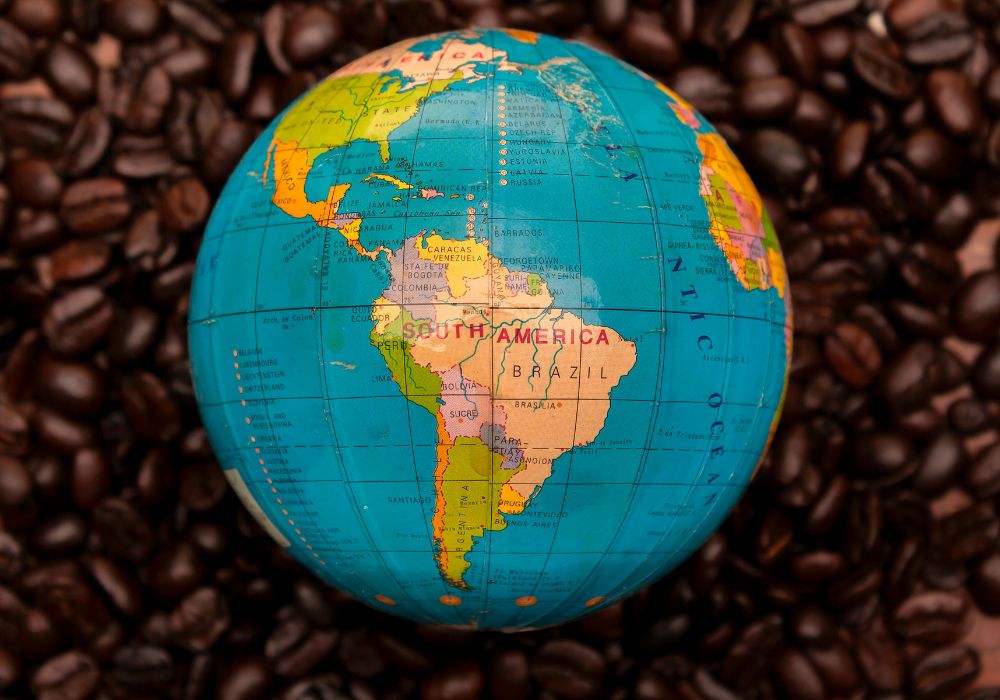
LatAm economies will lose momentum in 2026, but some will fare better.
We believe APAC will remain the strongest global performer in 2026. However, the growth trajectory will likely be more uneven than in past cycles.
Prospects appear solid for global industry in 2026, but activity is set to remain regionally and sectorally divergent.
We think 2026 will be another challenging year for the UK economy – our GDP growth forecast of 1% is at the bottom of the consensus.
Real estate is still poised for a revival in 2026. Although 2025’s deal recovery was delayed, the key fundamentals remain in place for renewed momentum.
We expect the Eurozone economy to gain momentum in 2026, but without a strong policy boost, its economic growth will be lacklustre.
Some very smart people are betting that machines shaped like humans will do much of our household and factory work for us in the near-ish future. But hurdles remain.
COP 30’s agenda had placed a strong emphasis on countries’ implementation of their emissions reduction target and, for the first time, several workstreams included discussions on unilateral trade policies.
We expect the global valves market to register an increase of 3.0% in 2025 and 3.1% in 2026. The downgrade is largely due to a weaker outlook for growth as a result of the impact of tariffs.
US exceptionalism will continue in 2026—but so will the vulnerabilities beneath the surface.
We expect steady but unexceptional global GDP growth in 2026, with more interesting developments beneath the surface.
As we head into 2026, our attention is turning to the key themes for next year. But how did our key calls for 2025 pan out?
Looking ahead, we anticipate a modest contraction in 2026 for aggregate commodity prices, with US natural gas and precious metals likely to remain relative outperformers.
