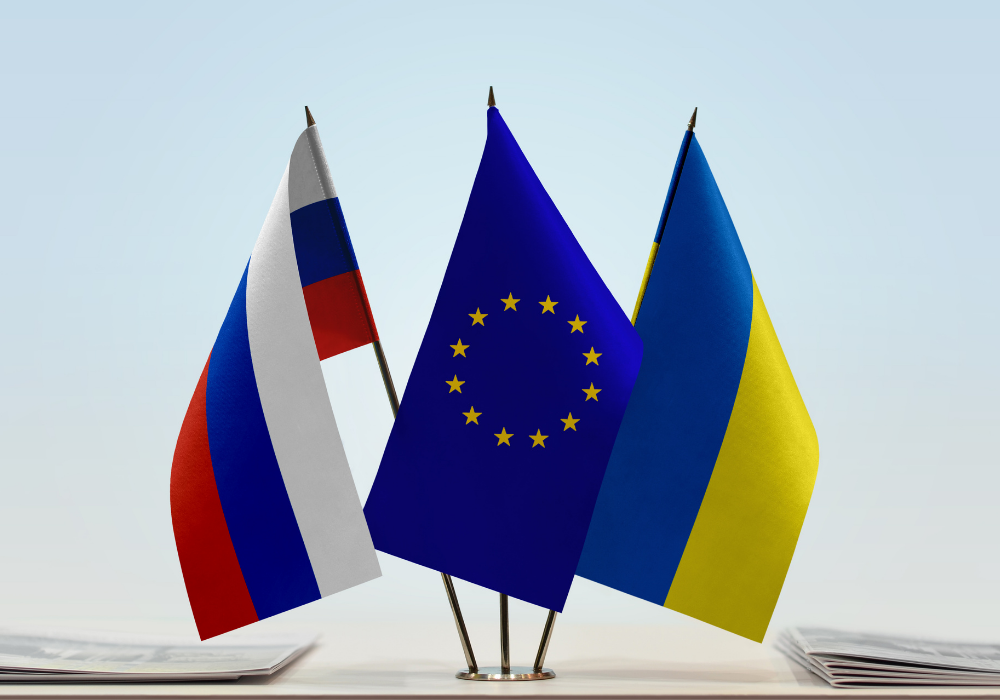
Russia’s huge oil and gas reserves, and the systemic importance of some commodities that are exported by Ukraine make the two countries a key part of the global supply chain. Europe in particular is heavily reliant on Russia for its energy needs, with 27% of EU total crude oil imports and 41% of total EU imports of natural gas coming from Russia.
Kimberly Cabello
Supply chain conditions remained highly strained in April, though cooling goods demand helped ease pressures modestly. Inflation stress increased for a fourth straight month. Challenges within logistics eased according to our tracker, but we take this reading with a grain of salt since the improvement was partly artificial as China’s lockdowns slowed trade flows at US ports and weighed on business activity. Meanwhile, news from the labor and activity fronts was encouraging, and inventory dynamics modestly improved.
Our analysis of property total returns and inflation suggest that the apartment sector is best positioned to weather the inflation storm in the US. While there is some variation by city, most US cities we analysed had apartment returns that were relatively well insulated when acyclical inflation is high nationally.
Investors in private markets can benefit from geographic diversification to help minimize their specific market downside risks, to participate in global economic growth, as well as to reduce their exposure to inflation risks and stretched valuations. Investors are starting to take notice, with allocations to traditional U.S. based private markets showing signs of decline.
The recent pullback in equity prices has provided some additional headroom for valuations and means that we now forecast slightly higher returns for equities over our strategic forecast horizon. Our latest baseline forecast is a 4.2% annual return in USD terms for the global index, up from 3.4% last quarter, with 4.0% expected for advanced economies and 5.9% for EMs.
As Western Europe accelerates a structural shift away from Russian energy dependence, Africa could play a salient role in filling the void. The longer-term transition towards renewable energy and a shorter-term reduction on Russian hydrocarbon dependence will increase demand for African renewable and non-renewable resources.
With Covid-19 restrictions lifting, and relatively little direct exposure to the Russia-Ukraine situation except through commodity prices and supply disruptions, the focus for Canadian metros switches to the post-recovery outlook for the next five years. We forecast a return to a more usual pattern of growth, with job gains in metros mostly outstripping those in non-metro areas by some distance.
Oxford Economics’ new construction forecasting service provides a comprehensive outlook to 2050 for construction activity across three categories of spender in the United States: the private sector, the federal government, and state/local government. Forecasts are updated once a quarter, and cover 18 types of construction across residential, commercial/industrial, and infrastructure.