OE Logo

The senior population continues to migrate to Sun Belt metros, but the trend has abated as more seniors are deciding to age in place than in previous generations. Top destinations for net in-migration of those 65 and over include many locales in Florida, South Carolina, and Arizona, but others have emerged as retirement hubs.
Our latest scenario analysis suggests that the global economy would falter in the event of an escalation of the Israel-Hamas war that severely disrupted the global supply of oil. But assuming the disruption was not protracted, we think any global recession would be mild and fleeting even if oil prices reached $150pb.

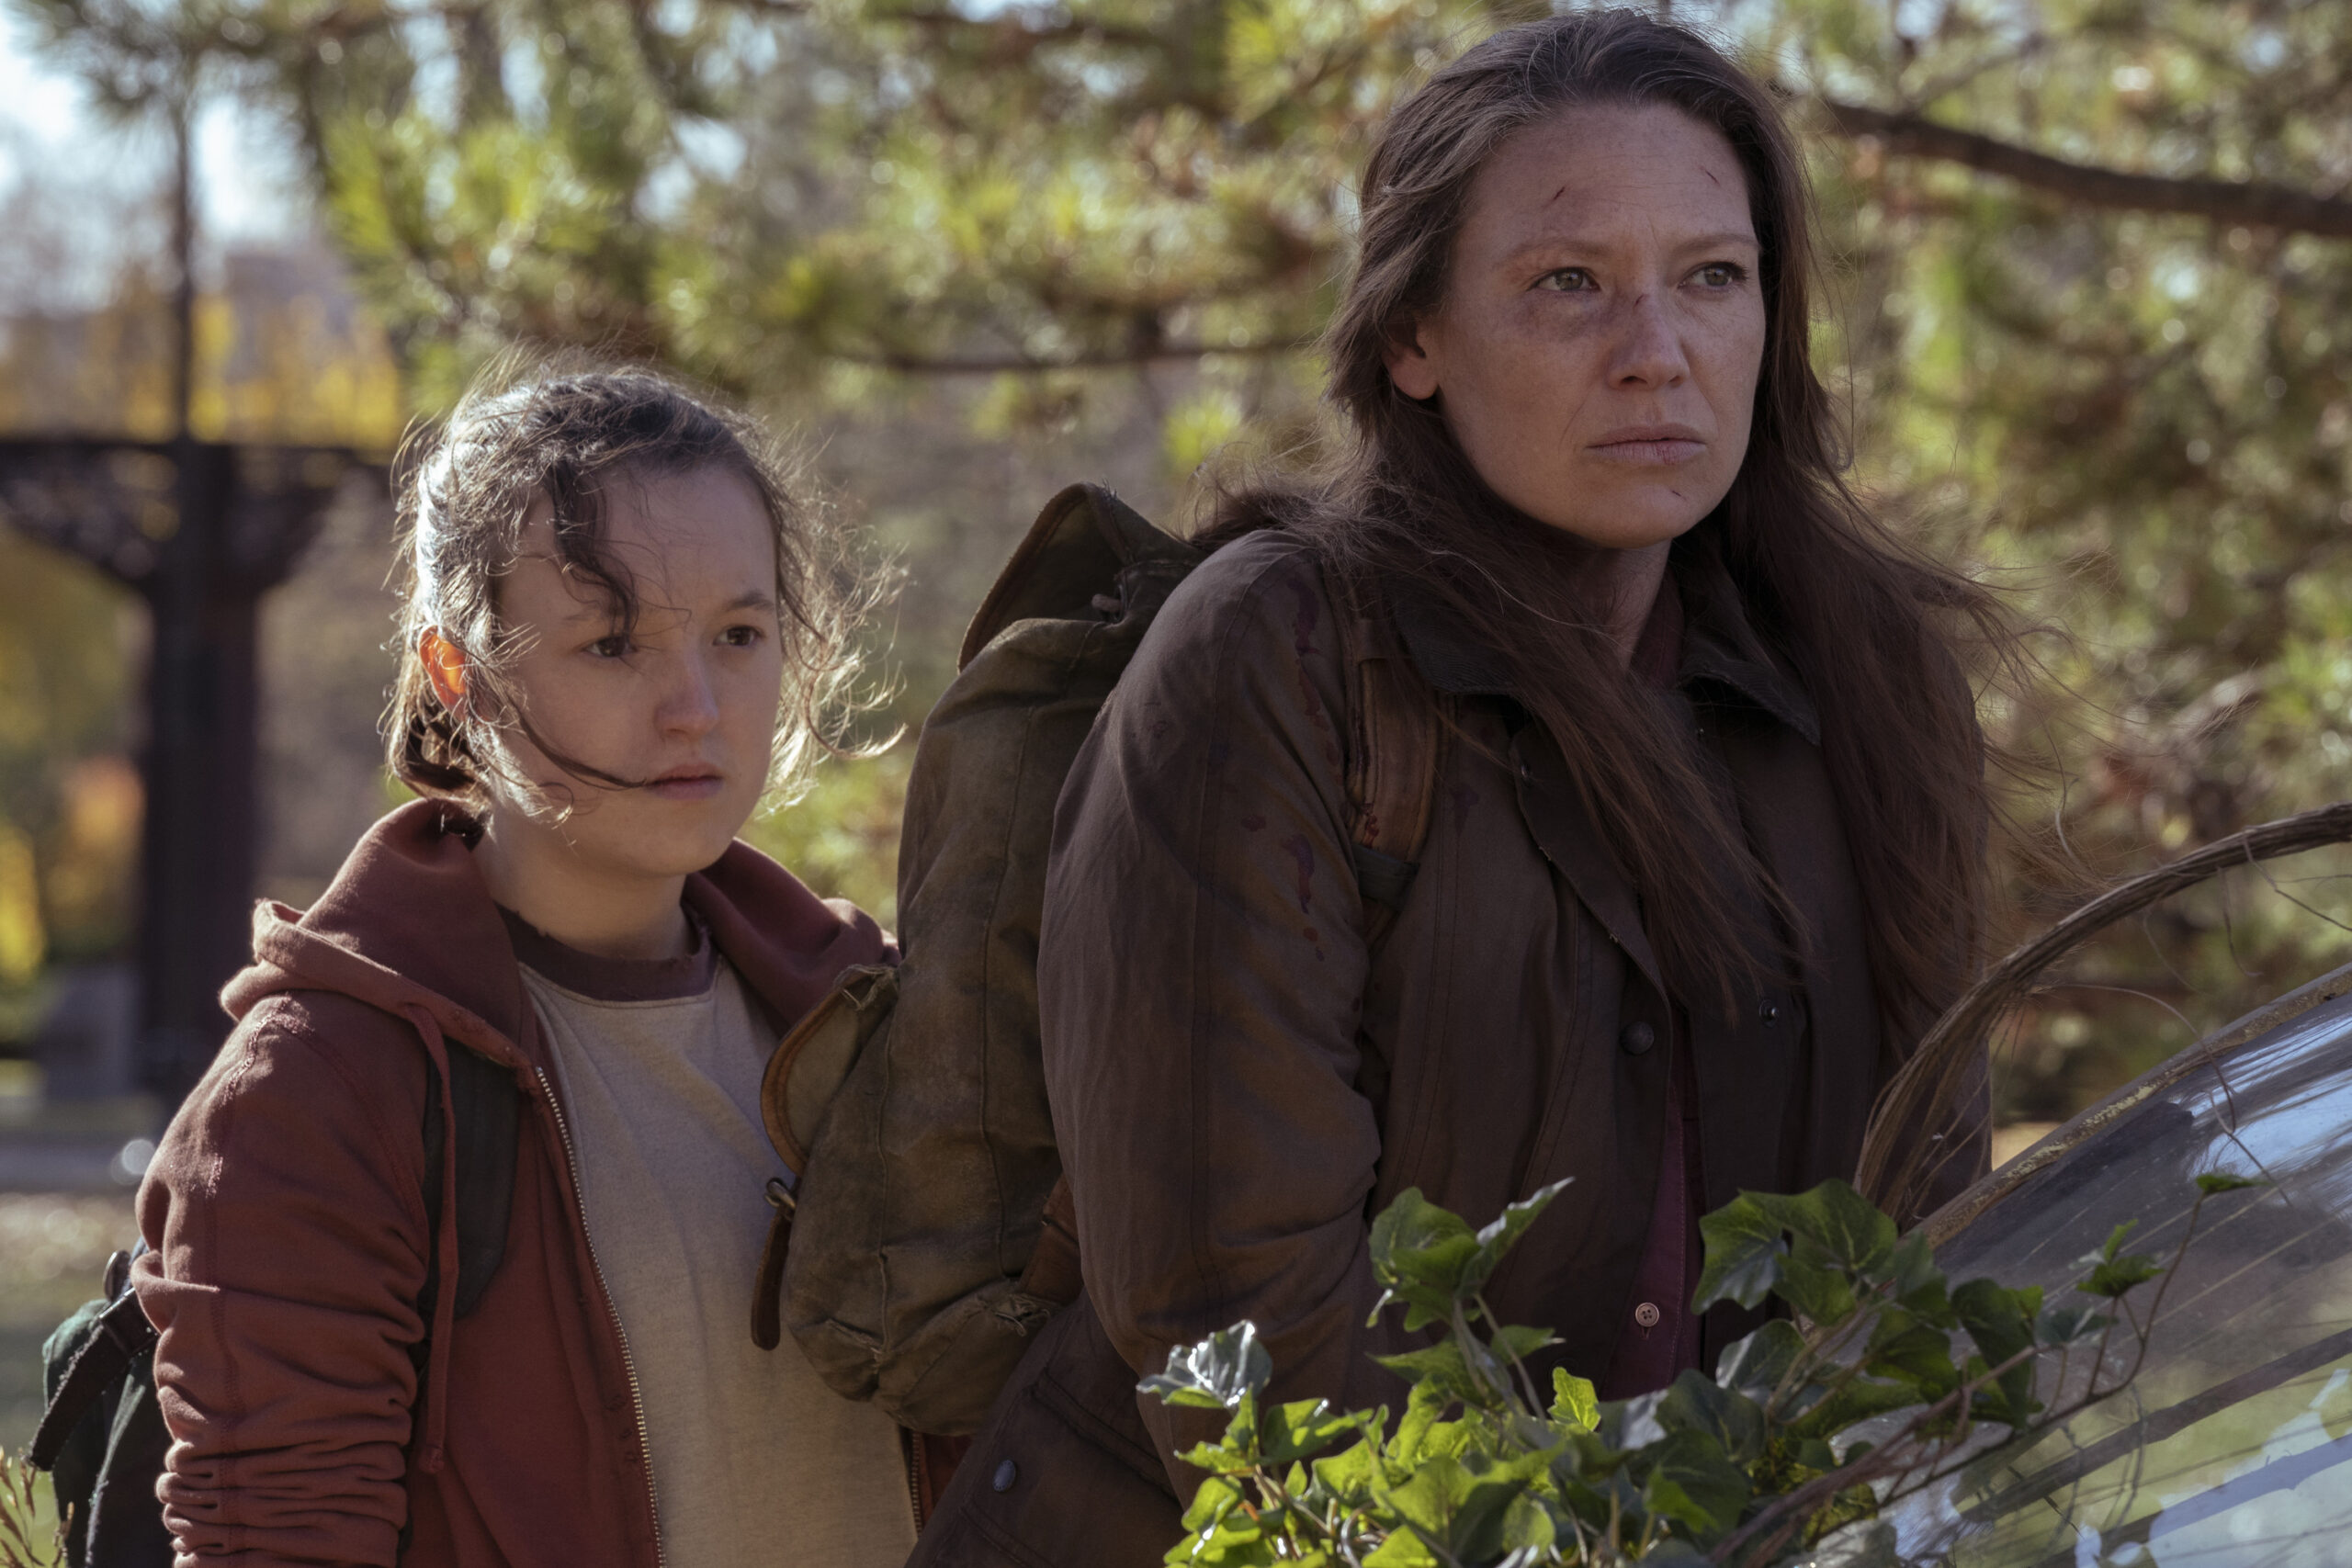
This study, commissioned by the Motion Picture Association – Canada (MPA), focuses on the first season of the show, “The Last of Us”, and analyses the production’s total economic impacts in Alberta from July 2021 to June 2022, when the first season was filmed. The study also considers the wider impact on boosting Alberta’s economy.

Our new Tourism Economics survey – Tourism Industry Monitor (TIM) – identifies optimism as industry experts expect global destinations to surpass 2019 performance in Q4 2023.

Additive manufacturing (AM) technology, more commonly known as 3D printing, has grown at a CAGR of 20% between 2016 and 2022 and will continue to grow as its applications across industries expand, innovative raw materials become available, and countries seek to protect themselves from supply chain disruptions.

US equities dipped into correction territory last week and we see the risk of more downside in the near term, as valuations remain expensive relative to safe assets, investors have yet to capitulate, and earnings momentum is stalling.

The EU’s Carbon Border Adjustment Mechanism (CBAM) is one of the central pillars of the EU’s Fit for 55 Agenda, which envisages reducing the bloc’s net greenhouse gas emissions by at least 55% by 2030 compared to 1990.

Our new global relative return index (RRI) signals that commercial real estate (CRE) investment opportunities should slowly and selectively emerge next year before becoming more widespread in 2025. At this point, our baseline expected returns move higher than required returns, pushing the global all-property index above the 50 mark.

We expect eurozone inflation will fall below the European Central Bank’s target in H2 2024. This is one of our key out-of-consensus views that puts us below the ECB’s forecast. Our call relies primarily on more pronounced disinflation from consumer energy and food prices than the ECB assumes. We anticipate a stronger slowdown in core inflation, given our weaker growth outlook.

As term premia reprice higher, a modest increase in duration is warranted, however, we think the opportunities lie at the end short end of the curve.

In this week’s Beyond the Headlines, join Javier Corominas, Director of Global Strategy, to look at the why ECB pricing and eurozone yield curves may be mispriced.

We see the recent increase in term premia as explainable by the ongoing retreat of price insensitive foreign buyers, structurally lower banking sector holdings, the drag exerted by the Fed’s balance sheet reduction (QT) and a recent uptick in inflation expectations volatility.

Following a year of subdued global growth in 2023, we think a further softening of economic conditions is likely next year. Inevitably, this is reflected in the outlook for the world’s major cities, which in aggregate, will also see slower growth in 2024 than this year.

Even as commercial real estate investment declines, there are still pockets of opportunity in the sector and we think those sectors set to benefit from the turn in the demographic cycle – life science, medical office, and medical retail (medtail) – are best positioned to outperform the broader sector.

Stricken sovereigns are suffering as China and the Western-dominated IMF Board engage in a titanic wrestling match over crisis-resolution architecture. It’s a massive problem that could be a destructive force for decades.

We’ve recently revised up our forecasts for US and UK bond yields in the long term by 50 basis points; we’ve also revised up Japanese and German yields by 20 to 25 basis points.

While the economy has expanded throughout 2023, uncertainty remains high and we are not ready to remove a recession from our baseline forecast.

The divergence in yield curves across markets has been notable, with most experiencing significant upward shifts in the last two years. Japan, however, stands apart from this trend, presenting a unique opportunity for commercial real estate investors to focus on Japanese assets for both leveraging and currency hedging.

Recent revenue performance of the tech sector tells a consistent story of industry’s leaders and laggards and confirms Oxford Economics’ forecasts for a significant shift within spend on enterprise technology as it enters a new era after the strong quarter century leading up to the pandemic.

Our growth outlook for Latin America is lower than the IMF’s forecasts, published today. A key area of difference is our views on US prospects. We expect the US to enter a mild technical recession soon and other advanced economies to cool significantly due to their higher-for-longer monetary policies.

In our latest Roundtable, “Finding opportunities in a global downturn”, Javier Corominas, Director of Global Macro Strategy, examines why we think equities are still expensive.