OE Logo

We think risk assets will underperform in 2024. In this week’s Beyond the Headlines, Javier Corominas, Director of Global Strategy, suggests that caution is warranted on credit and developed market equities, but sees a recovery in European small caps in the second half of the year.
Global urban consumers have faced numerous difficulties in recent times, and the near-term outlook looks challenging still. Rising interest rates will take over from high inflation as the main drag in the short-term consumer outlook.

Emerging market (EM) GDP growth will disappoint next year but EM central banks will reap the dividends of credible policies during the era of supply shocks; we identify five emerging market themes for 2024.

We think risk assets will underperform in 2024. We map out the implications of our key 2024 global macro themes for asset allocation.

Every year, the Conference of the Parties on Climate Change captures the world’s attention for a few weeks as government, scientific and business leaders take stock, align activities, and strive for real progress on climate change — as is currently underway at COP28 in UAE.

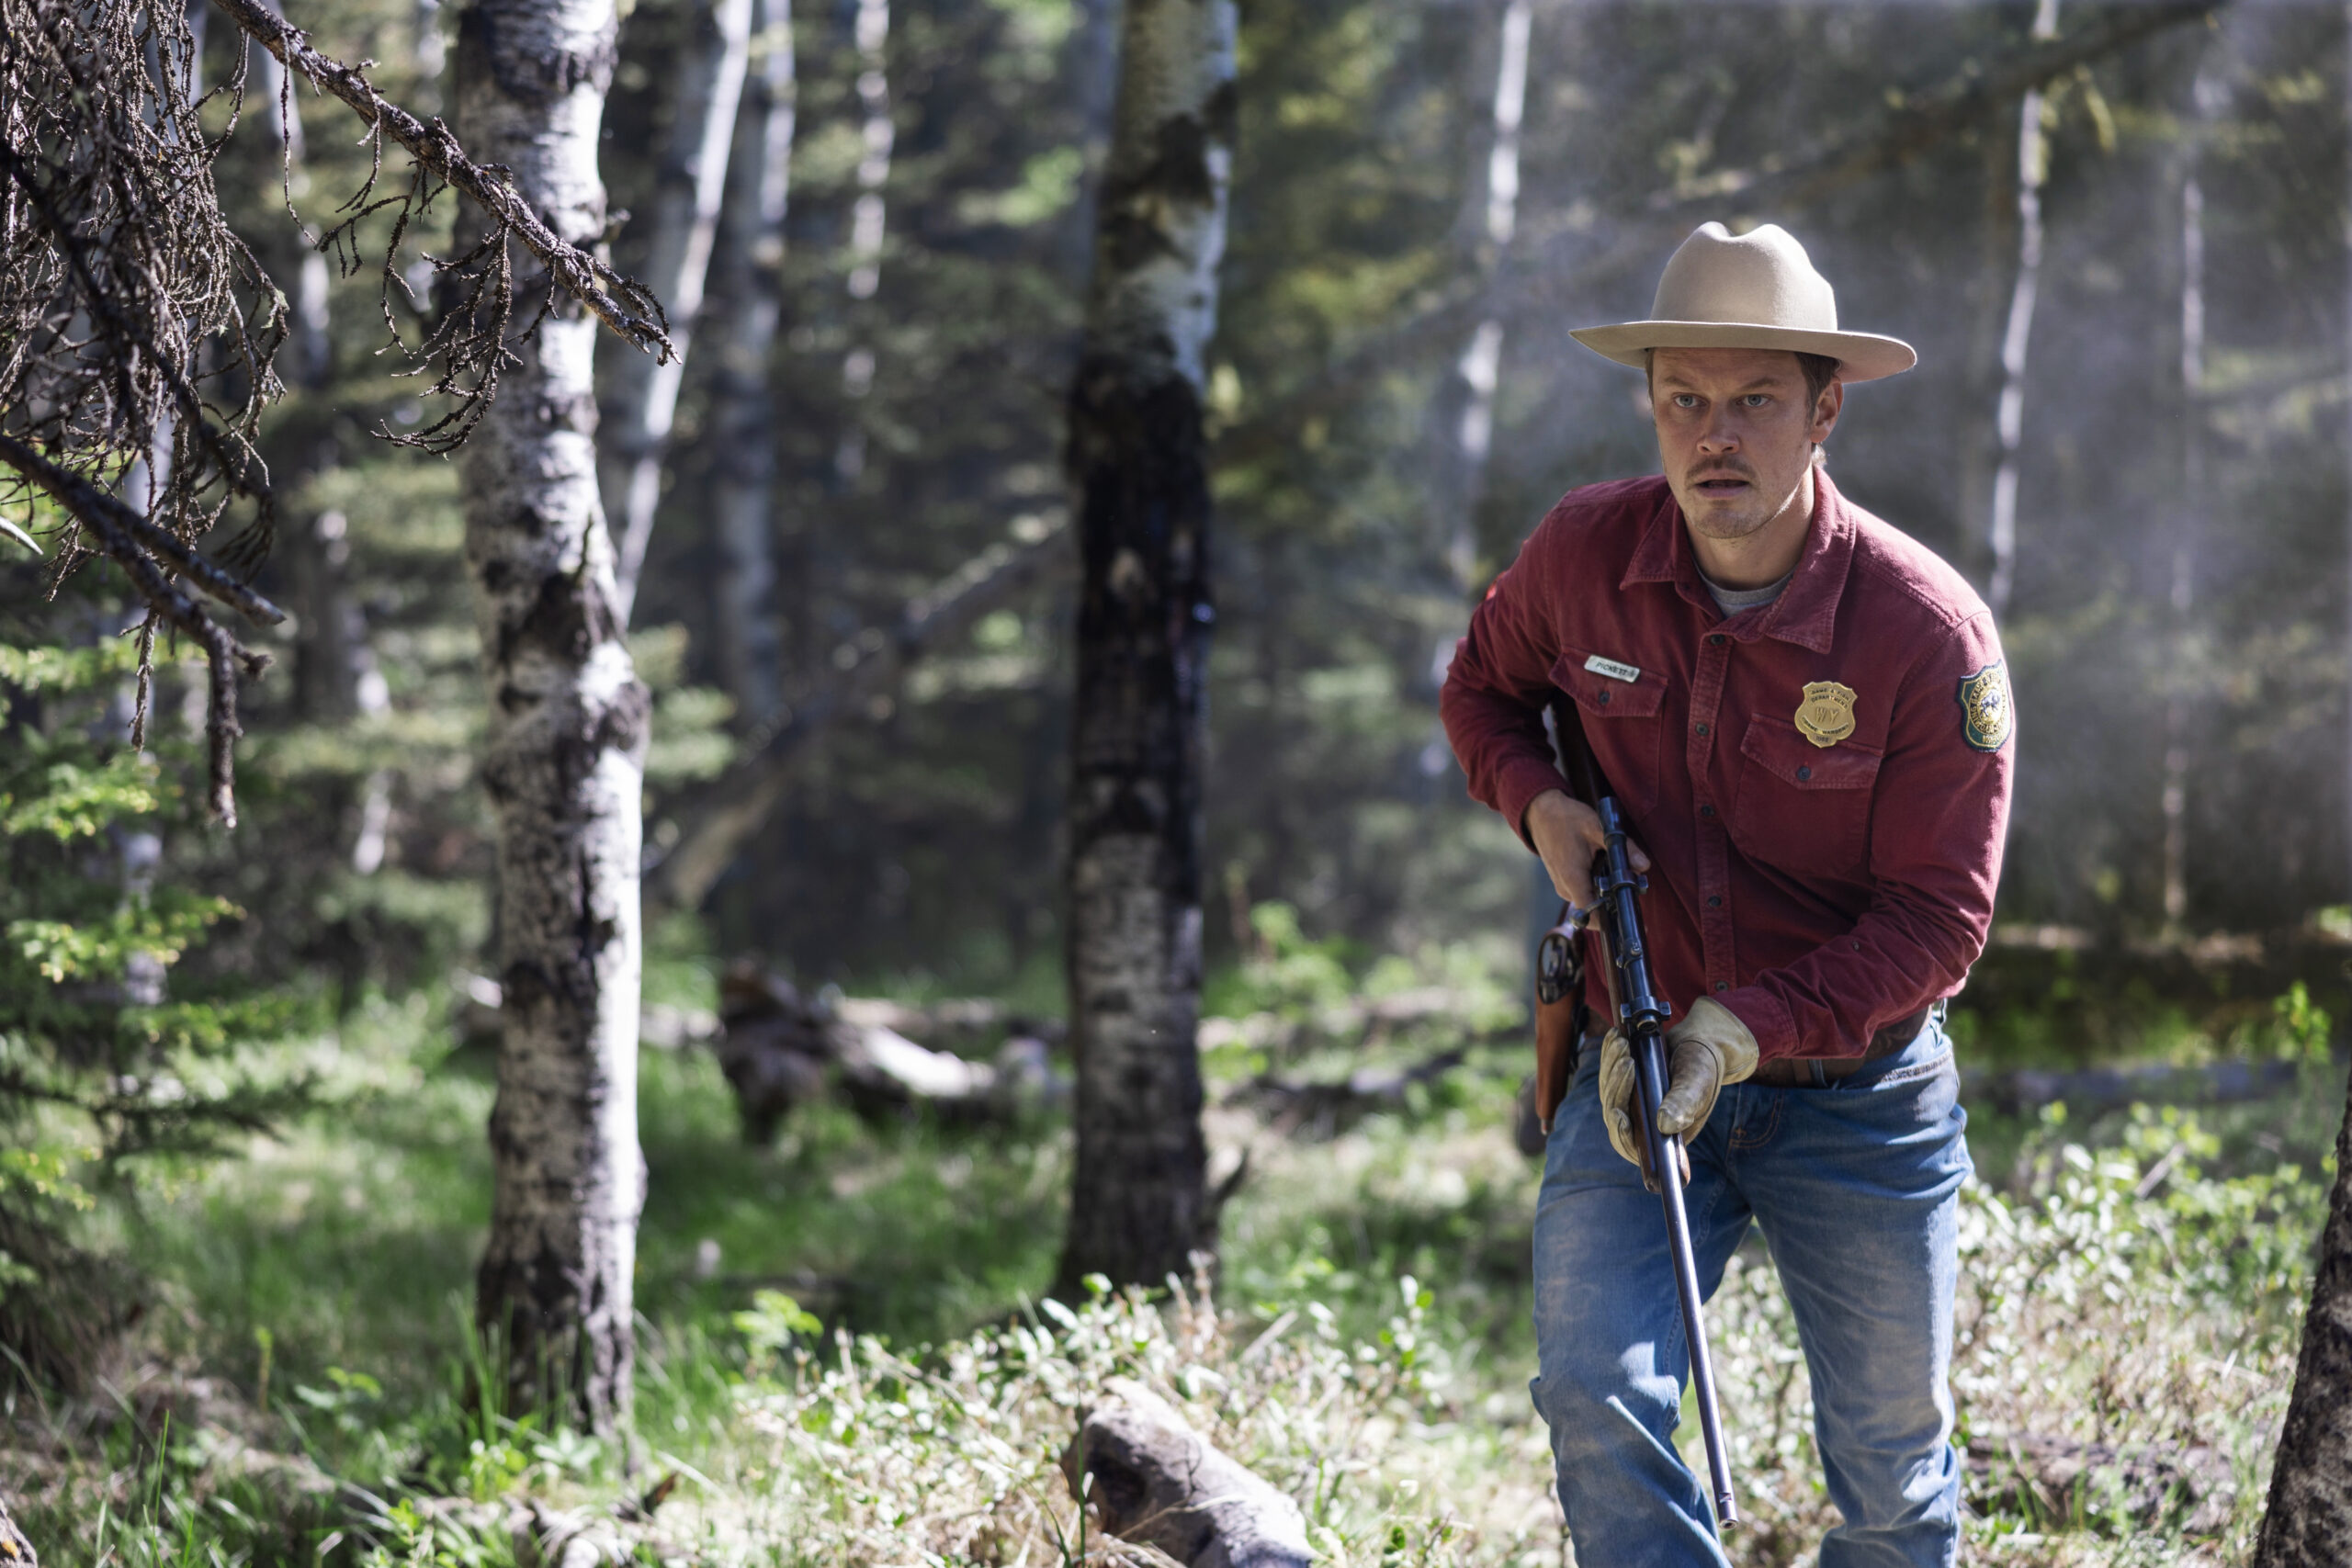
This study, commissioned by the Motion Picture Association (MPA) – Canada, focuses on the second season of the show “Joe Pickett”, and analyses the production’s total economic impacts in Alberta, Canada, in 2022/23, when the second season was filmed. The study also considers the wider impact on boosting Alberta’s economy.

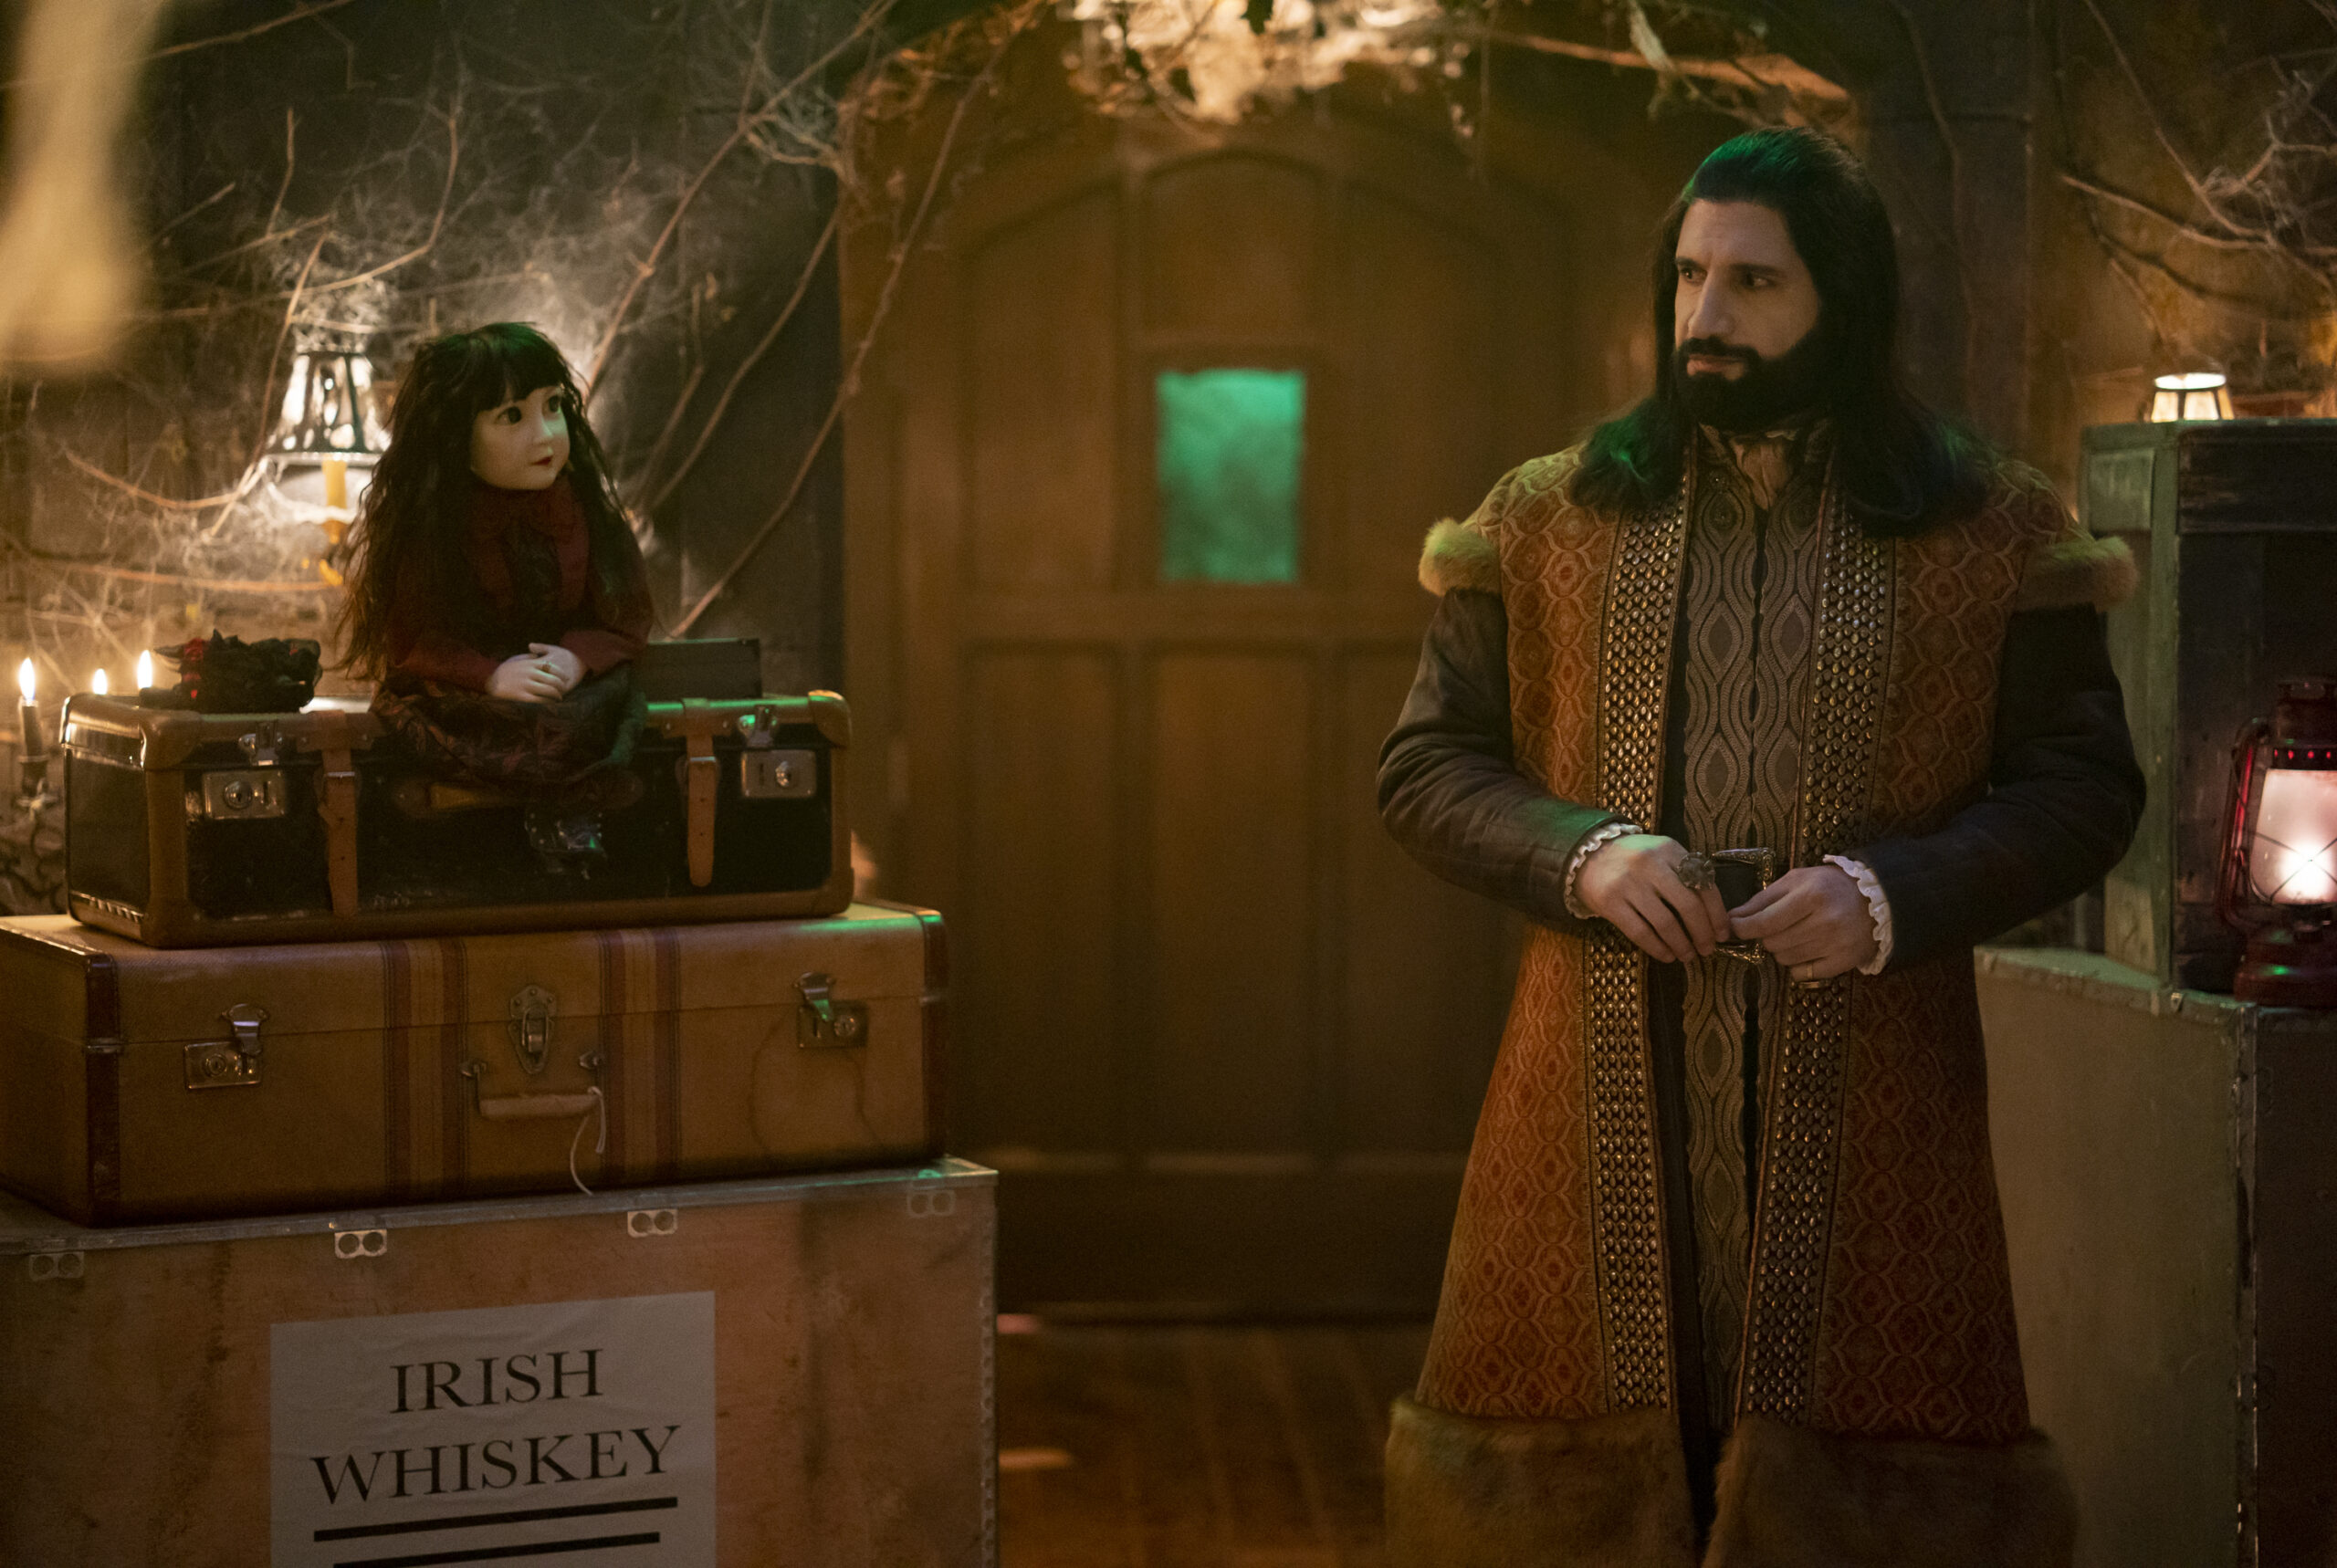
This study, commissioned by the Motion Picture Association (MPA) – Canada, focuses on the fourth season of the show “What We Do in the Shadows”, and analyses the production’s total economic impacts in Ontario, Canada in 2021, when the fourth season was filmed. The study also considers the wider impact on boosting Ontario’s economy.

Trade protectionism between the US and China has been intensifying over recent years, and this is increasingly raising concerns of an adverse economic fallout among businesses. In our latest Techonomics Talks, David Schockenhoff, Head of US Macro Consulting, examines these concerns and the potential economic fallout.

After nearly doubling in size from 2017 through 2022, the warehousing and storage sector shed jobs over the last five quarters as the industry corrected for the slowdown in e-commerce spending growth. Job growth within the warehousing sector had been widespread as nearly every metro enjoyed job gains in 2020 through H1 2022.

Our measure of financial conditions has become less restrictive in the US and started to loosen in the eurozone and the UK, reflecting investors’ expectations that interest rates have peaked. This should aid the outlook for commercial real estate (CRE) on the margins, although the scale of past rate hikes, sluggish economies, and structural headwinds mean the sector still confronts challenging fundamentals.

Our new demographic projection suggests rapid international migration will boost Canada’s population to 42mn by 2025, which would be a record 3mn (8%) increase from 2022. The surge in population has important implications for the economy, which we will incorporate in our December economic forecast.

The greenback is overvalued fundamentally, but 2024 will disappoint dollar bears. The pivot the market expects on the back of weaker data and a continued benign disinflation will take time to materialise. In this week’s Beyond the Headlines, Javier Corominas, Director of Global Strategy, suggests the dollar will remain strong in 2024H1 against major cyclical currencies.

The dollar will continue to be supported by a high carry and the relative resilience of the US economy. Even the recent loosening of financial conditions – itself based on the pullback in yields and a more flexible Fed – have only partially dented the USD bullish trend.

It’s widely believed that global growth and inflation will slow in 2024 and that advanced economy central banks will begin to pivot in H2. In this week’s Beyond the Headlines, join Ben May, Director, Macro Forecasting and Analysis, as he outlines the three key themes which we believe will have an important bearing on the precise path the economy and financial markets will take next year.

We expect a material slowdown in the US economy in the next couple of quarters to give way to a modest acceleration in GDP growth in the second half of 2024. In effect, the Fed will pull off a “soft-ish” landing. Inflation will continue to fall but at a much more gradual pace than in 2023 driven by a gradual loosening of labor market conditions.

We expect widespread declines in inflation and interest rates in 2024 across advanced economies. A key differentiator, however, is that the eurozone is likely to see a faster return of inflation to target and a sharper fall in interest rates than the US and UK.

In our latest forecast, we removed the mild recession from our baseline and now anticipate a prolonged period of below-trend growth. However, the risks of a recession are still elevated, so we will continue our recession monitor series, highlighting potential risks that could tip the economy into recession in the months ahead.

In the past week, our research has focused on the recent behavior of, and prospects for, interest rate-sensitive elements of GDP. In this week’s Beyond the Headlines, join Adam Slater, Lead Economist, as he examines how the relative resilience of G7 output in the face of aggressive rate hikes is partly due to the surprising strength in interest-sensitive parts of GDP.

The relative resilience of G7 output in the face of aggressive rate hikes is partly due to the surprising strength in interest-sensitive parts of GDP. This looks to be linked to factors like the limited weakening of asset prices and increased fixed-rate borrowing that has lengthened transmission lags. However, there could still be weakness ahead for these sectors.

One of our key macro calls for 2024 is our view that eurozone inflation will be lower than what the market and what the ECB expects.