


CPI inflation was weak once again in Q4, with the headline measure increasing by just 0.2% q/q. Inflation has now slowed to 2.4% y/y. The trimmed-mean measure increased by 0.5% q/q in Q4, which is an encouraging step down.
CPI inflation was weak once again in Q4, with the headline measure increasing by just 0.2% q/q. Inflation has now slowed to 2.4% y/y. The trimmed-mean measure increased by 0.5% q/q in Q4, which is an encouraging step down.
Join us for an insightful session on the evolving landscape of building and construction in Australia. Industry leaders will share insights on emerging growth drivers like data centres and public hospitals, alongside challenges from capacity constraints and cost pressures. Learn how policy shifts, institutional investments, and global resource demand are shaping the future, and discover strategies to position your business for success.
Together, they will provide the latest outlook and in-depth discussions on Australia’s Construction Sector.
Explore the shifting dynamics of the global economy and the critical challenges shaping growth and inflation in 2025 and beyond. As post-pandemic disruptions give way to new uncertainties, we’ll delve into fiscal sustainability, evolving interest rates, and their differentiated impacts on sectors, cities, and markets. Gain actionable insights from expert-led sessions on Australia’s economic outlook and the journey to net zero.
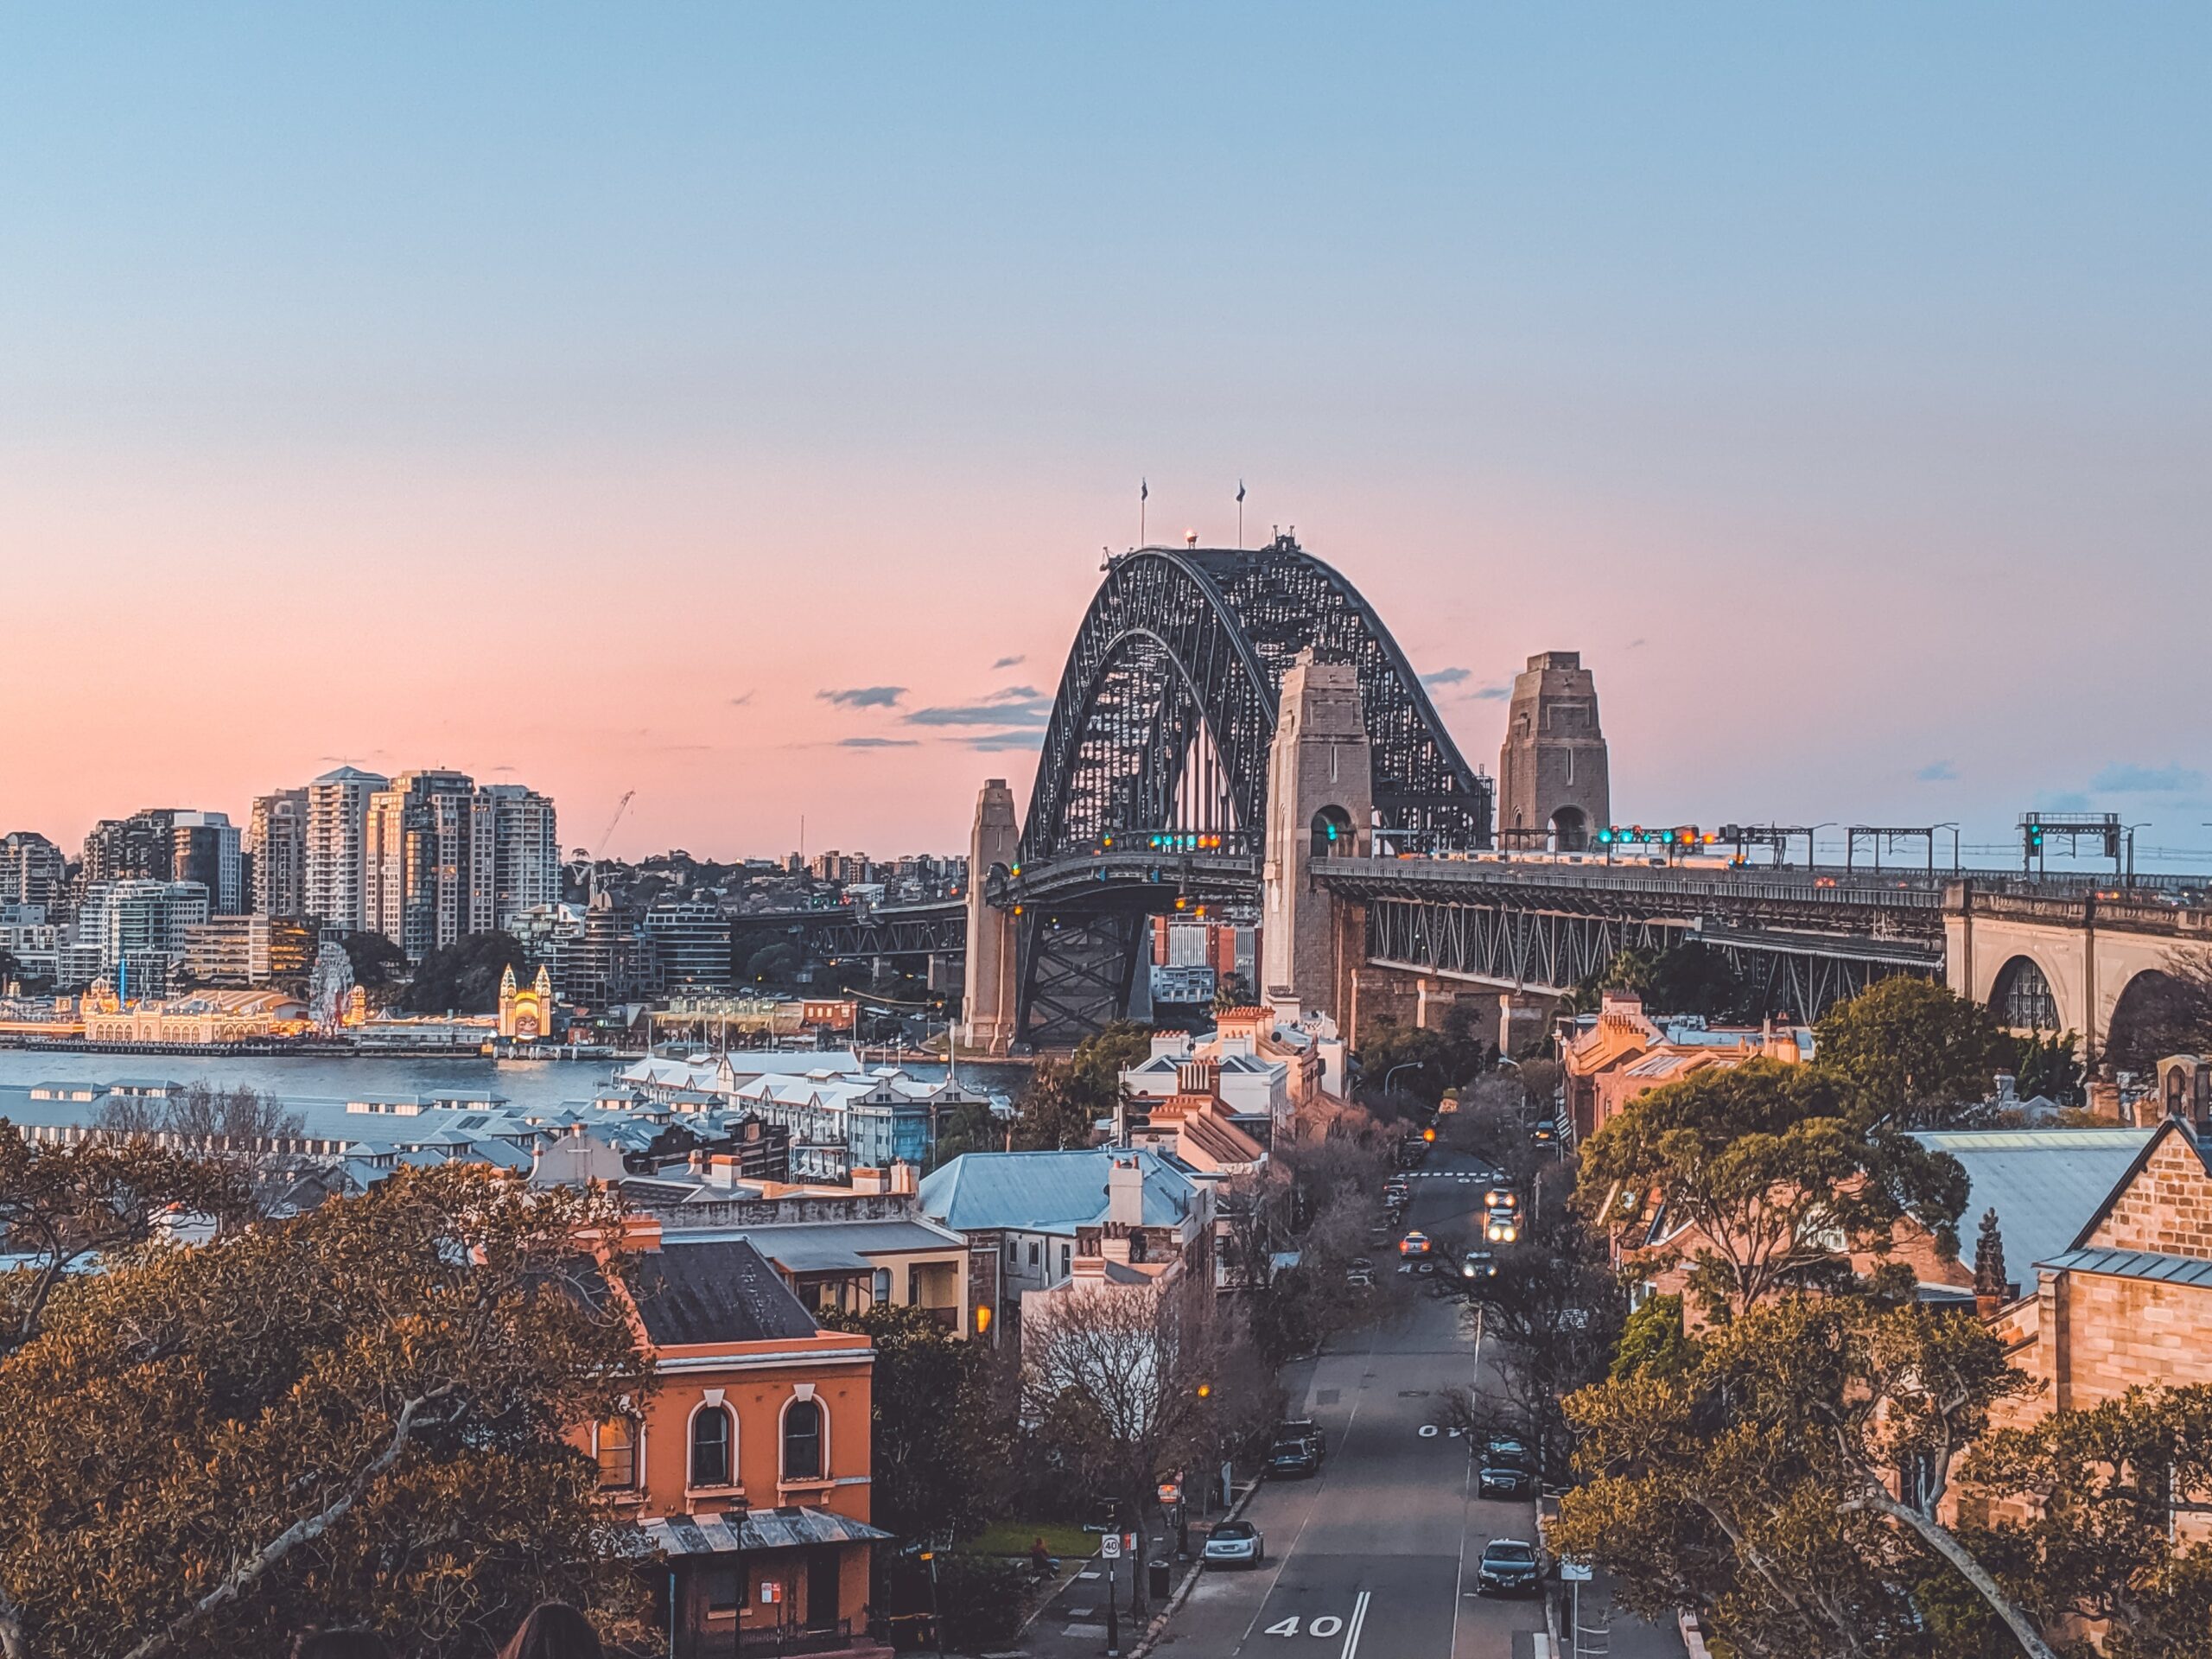
Sydney's 2022 Business Needs Survey: Shifts and Insights Oxford Economics Australia conducted a comprehensive analysis of the City of Sydney's 2022 Business Needs Survey, highlighting trends in business confidence, sector-specific recovery, changing business needs, and digital service expansion. Project background The City of Sydney commissioned Oxford Economics Australia to analyse the results of its 2022 … Read more
The Australian government is currently developing the 2035 greenhouse gas emissions target as part of its Nationally Determined Contribution (NDC) submission required by the Paris Agreement. Countries who signed onto the Paris Agreement are expected to set a 2035 NDC target before COP30, which is slated to be held next year.
October was another solid month for retail sales, with turnover increasing 0.6% m/m. Sales growth was driven by household goods in October, with retailers reporting a strong response to discounting activity.
We think Australia’s growth prospects are set to improve in 2025. Lower inflation will be supportive of the growth outlook, although there is still only limited scope for policy easing next year.

The road infrastructure sector is facing a serious skills shortage, exacerbated by the impacts of COVID-19, increasing demands on transport projects, and rapid technological advancements.
Uncover the critical role of investment analysis in Australia’s energy sector. Gain insights into cost of capital benchmarks for evaluating diverse energy projects.

Electricity construction activity continues to boom as Australia works towards its target of generating 82% of electricity from renewable sources by 2030.
Office property continues to be challenged globally by structural changes to occupier demand. This has impacted vacancy rates and rents and trigged large falls in capital values, to which Australia is not immune
The Federal government has changed tack on fiscal policy, signalling it will run a much easier stance of policy from next financial year.
The Australian labour market has outperformed expectations over the past two years. From a very tight starting point, employment has increased by 6.1%, and while the unemployment rate has risen, it remains low at 4.1%.
The government funded transportation infrastructure boom continues to support growth in engineering construction activity. Annual growth slowed to 6.4% over FY24 to be $34.9bn, the highest level on record. We expect activity to reach a cyclical peak of $36.9bn in FY26.
The wage price index increased by 0.8% q/q in Q3. Quarterly WPI growth has been steady at the same pace through 2024.
There were no surprises from the RBA at the November meeting, with the board keeping rates on hold at 4.35%.
Australia’s major metropolitan office markets are at the tail end of a major phase of supply that started in FY20 and will run to mid next year, in the process contributing towards the current substantial oversupply.

The labour market continued its very strong run in September, with employment shooting up by 64,100. The unemployment rate held steady at 4.1%, following a downward revision to the August figure, with the participation rate reaching a record high of 67.2%.
Through a period of higher but stable interest rates and cost of living pressures, the combined capital city (CCC) median all-dwelling price grew 7.5% over FY2024 to a fresh record of $987,600.
Vacancy in the Melbourne CBD continued to track higher during H1 2024, increasing to 18.0%, reflecting the
persistent contraction in office demand
