Region: Australia
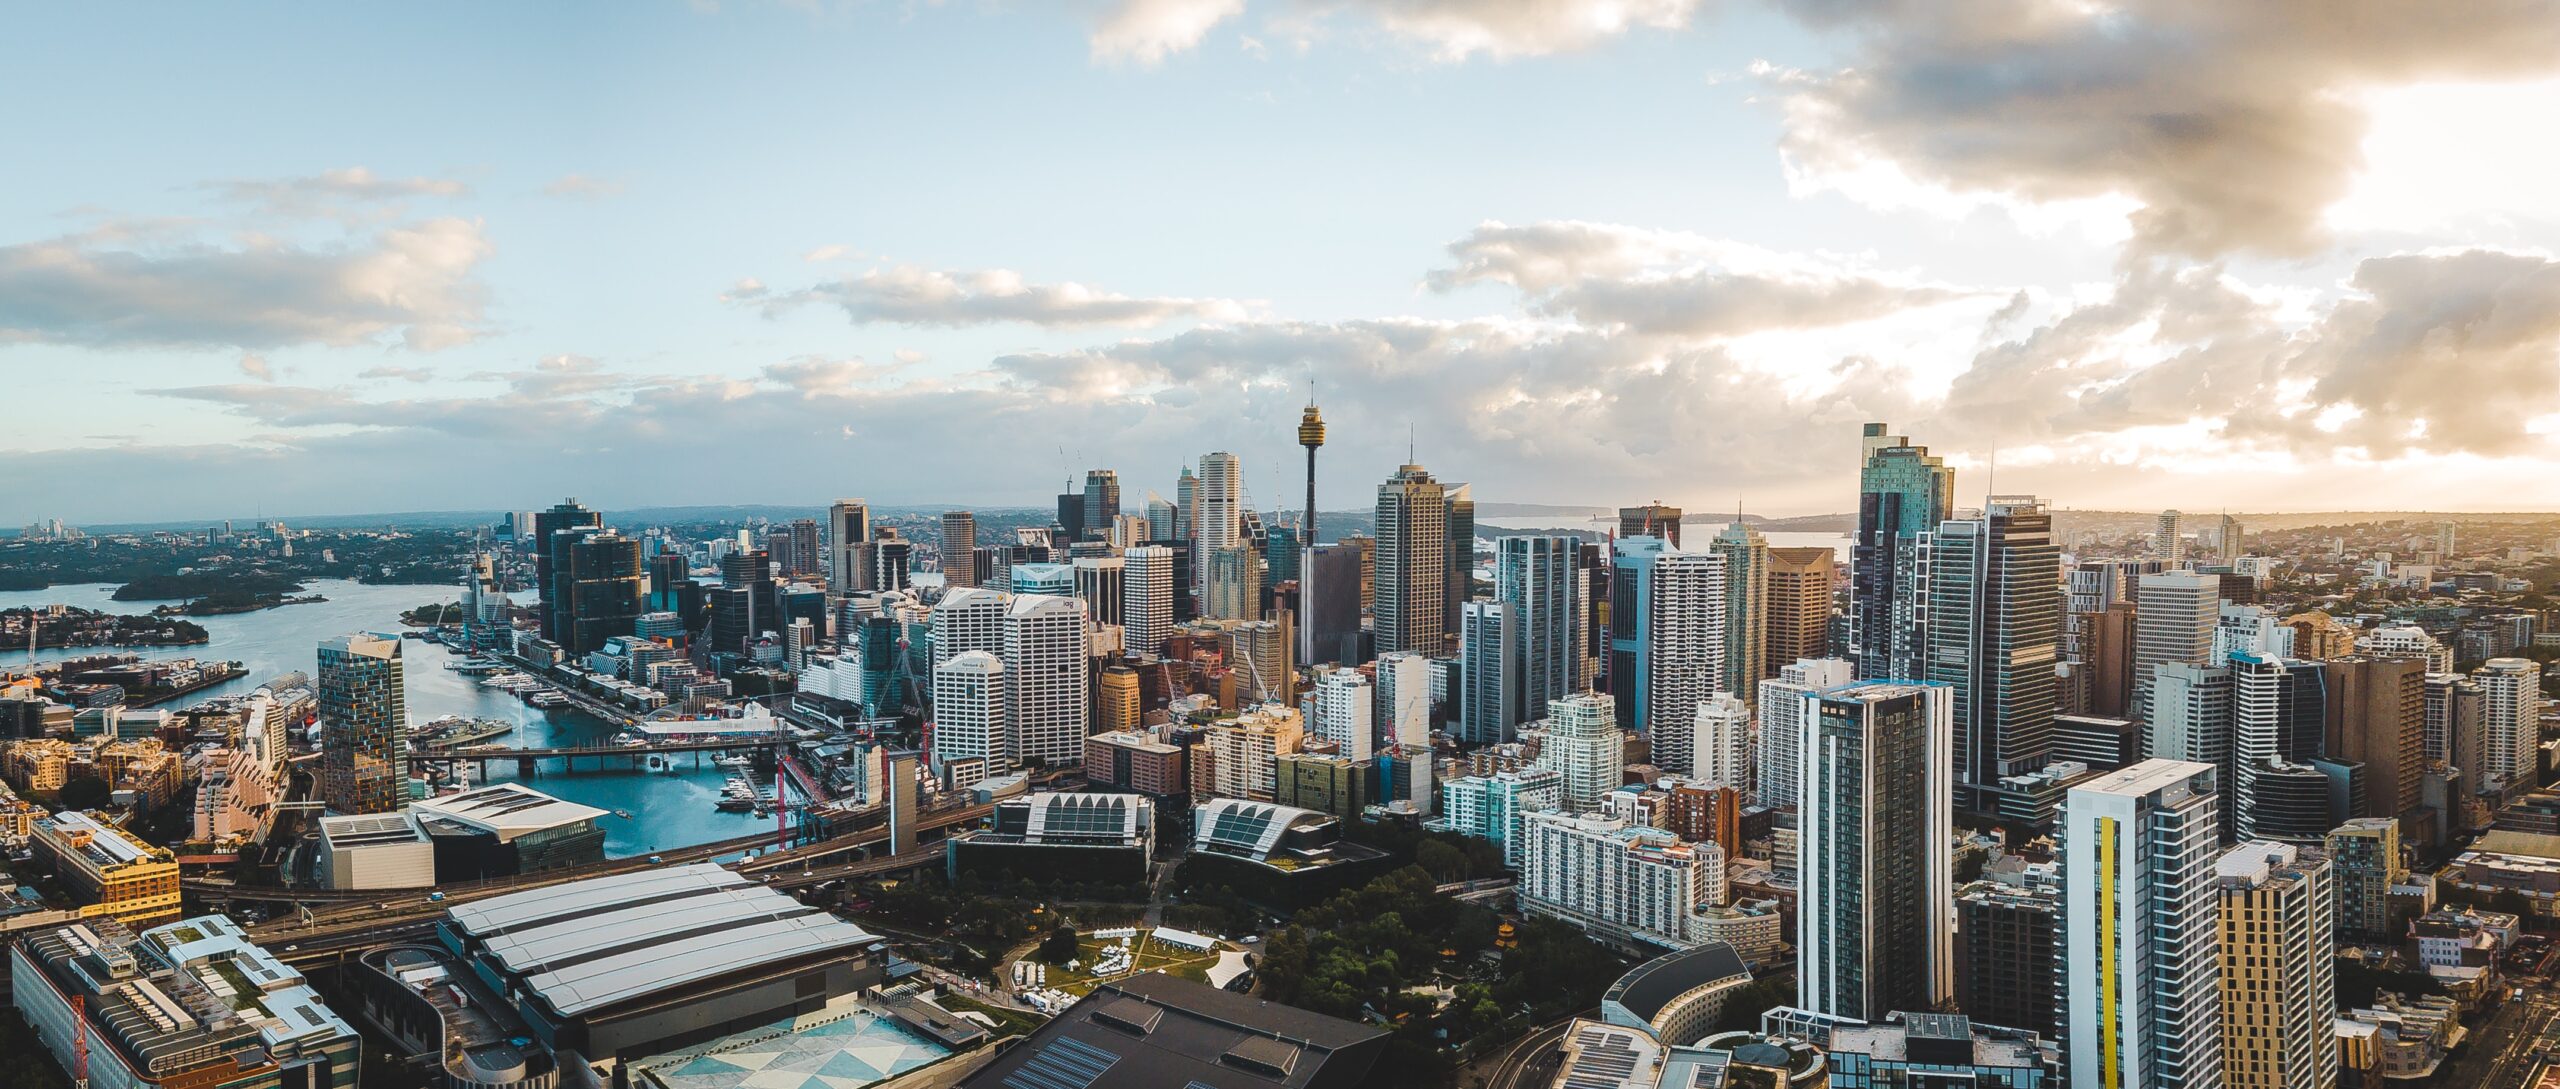
The office sector in Australia is facing several headwinds, including reduced demand from hybrid working arrangements, slowing economic and employment growth, and rising bond rates and yields. However, it may still present an attractive cyclical investment opportunity with astute timing and management of vacancy and incentive risks.
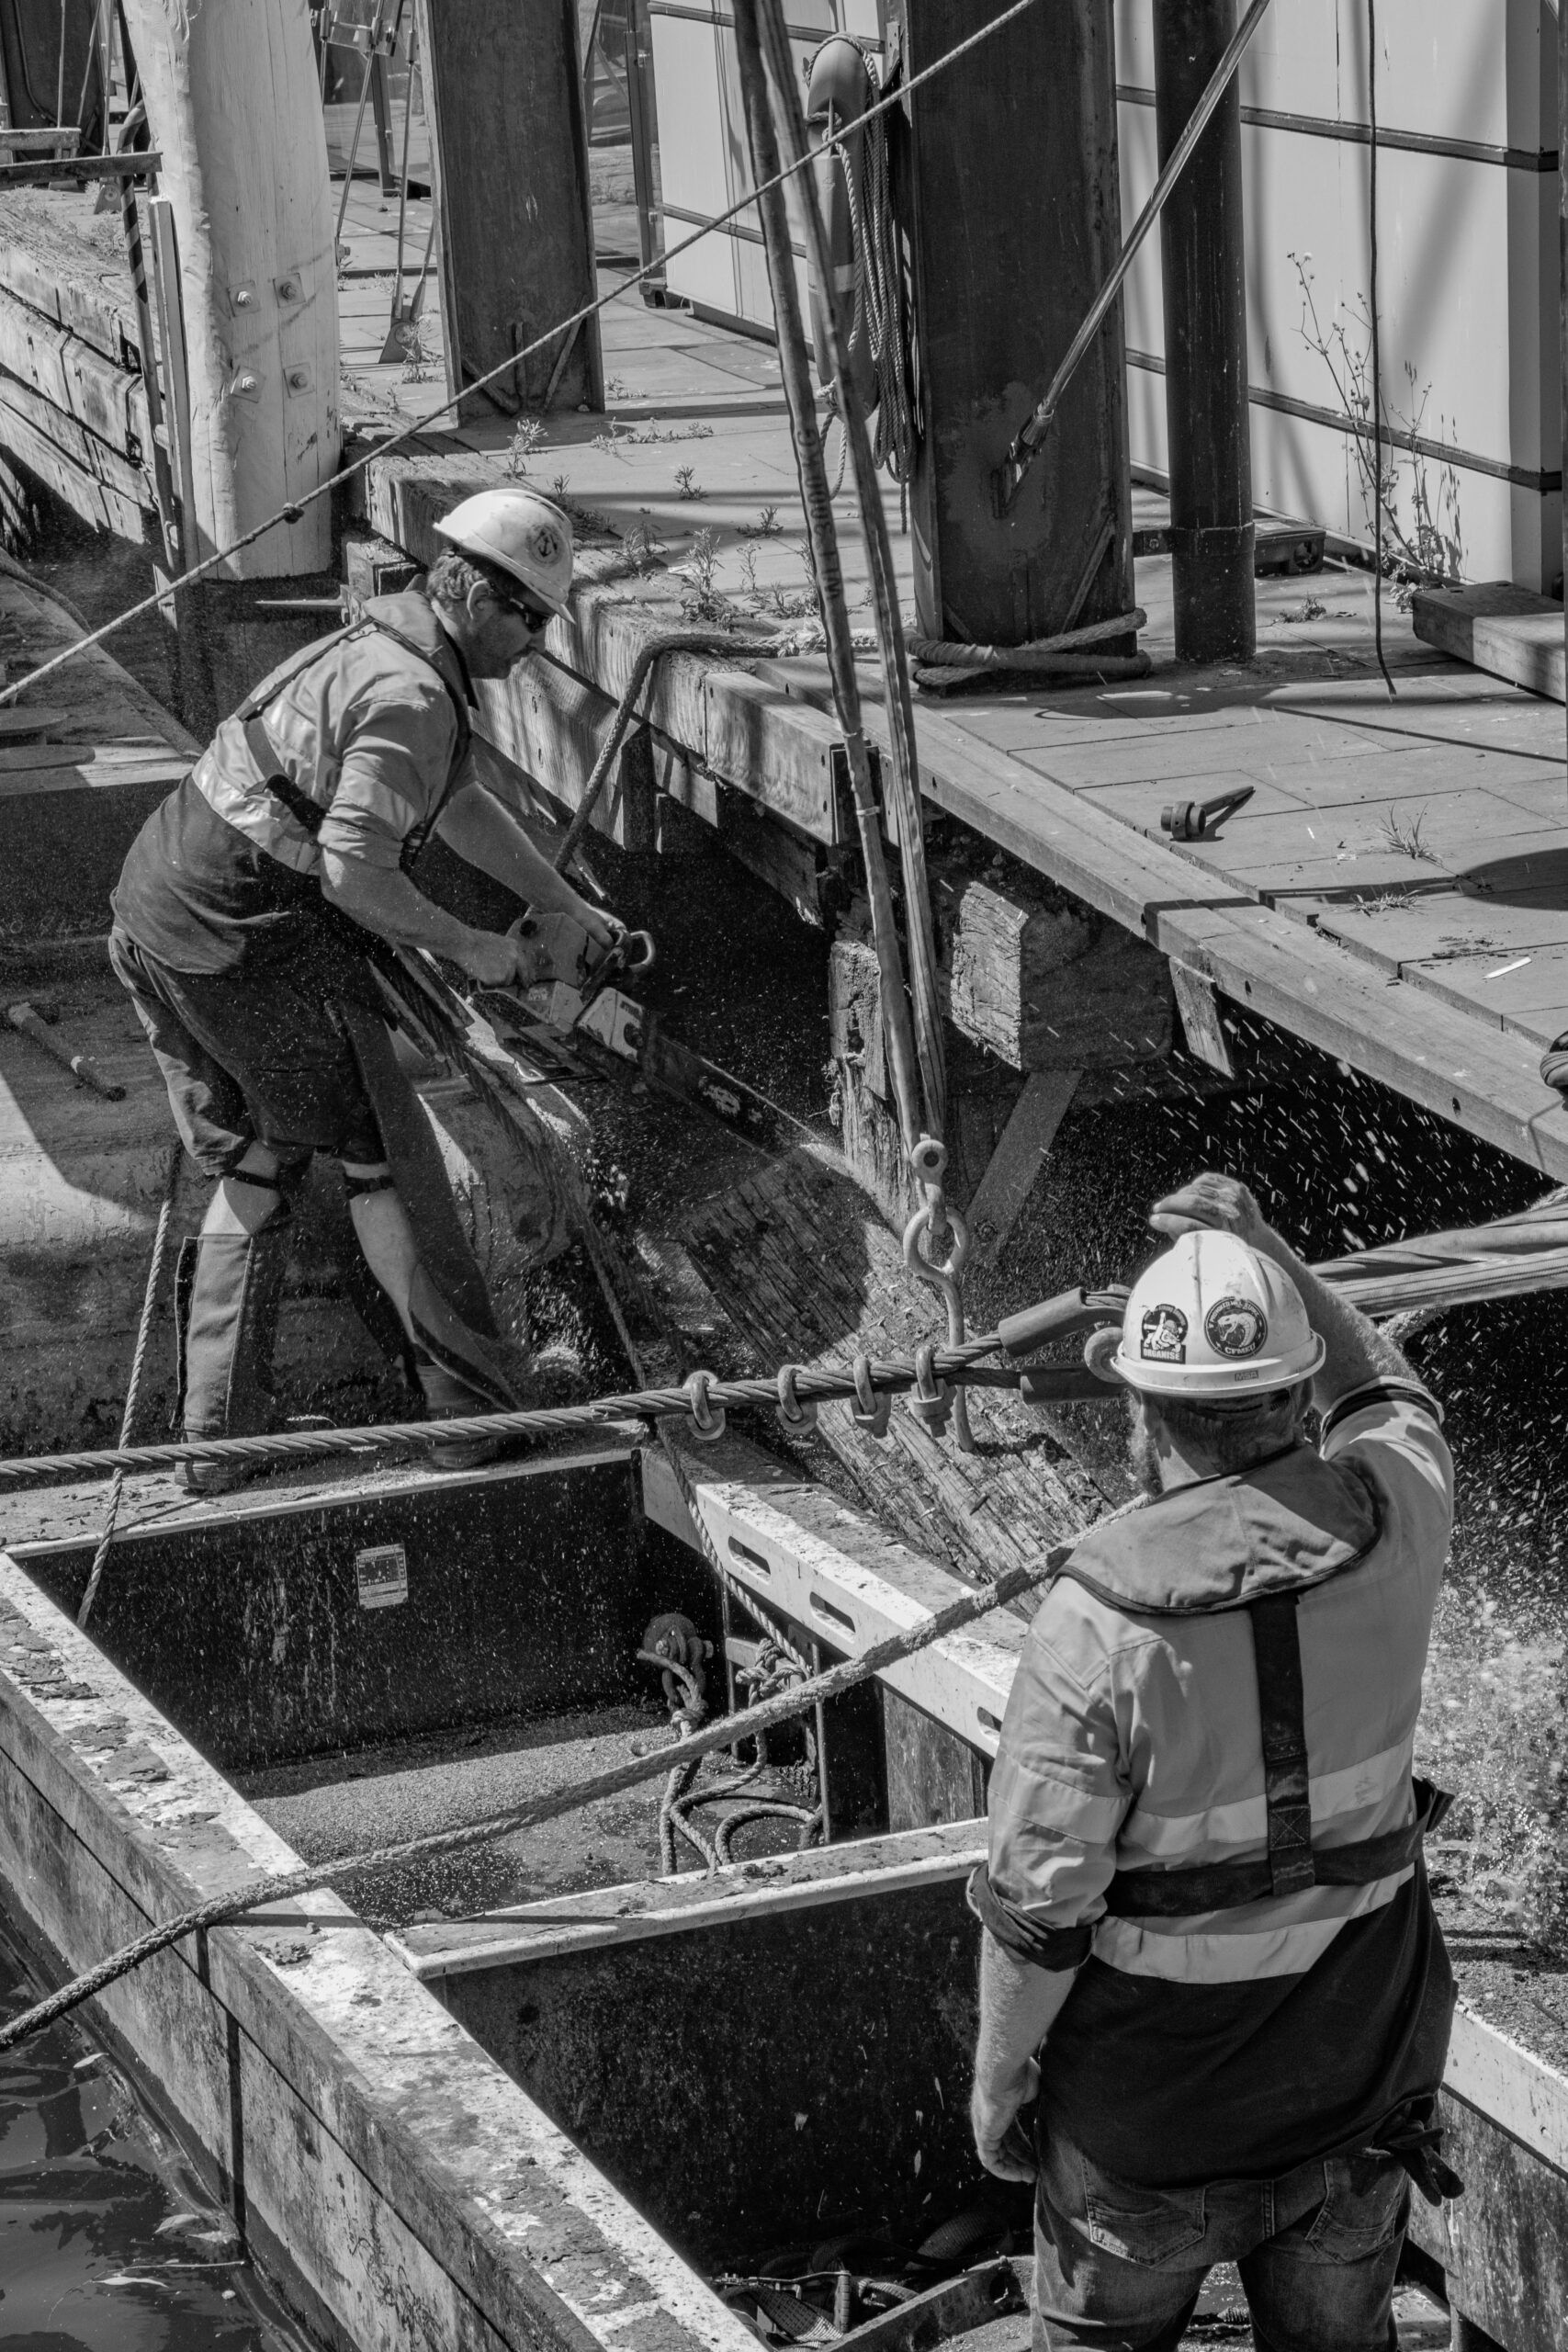
The National Transport Commission (NTC) and the Australasian Railway Association (ARA) commissioned Oxford Economics Australia to update and extend quantitative rail workforce capability modelling last completed in 2018 and published in the ARA’s report. Fundamentally, this report
seeks to explain how skills demand will form for the rail industry over the coming decade, what will be
the key threats to workforce capability, and what industry and governments can do to respond to meet the challenges of delivering on the significant rail infrastructure investment.
The fight against inflation is well underway across the globe, with most central banks either approaching or having already reached the peak of their hiking cycle. Additionally, geo-political
tensions and the possibility of increasing restrictions on trade between global rivals remains a key downside risk to the global outlook.
The passing of the previously delayed Housing Australia Future Fund (HAFF) means that all the Albanese government’s announced housing policies are now in place. These policies represent a minimum funding pool of $5.5 billion stretching to the end of the decade, potentially lifting as high as $10 billion if all targets are met and excess fund returns achieved.
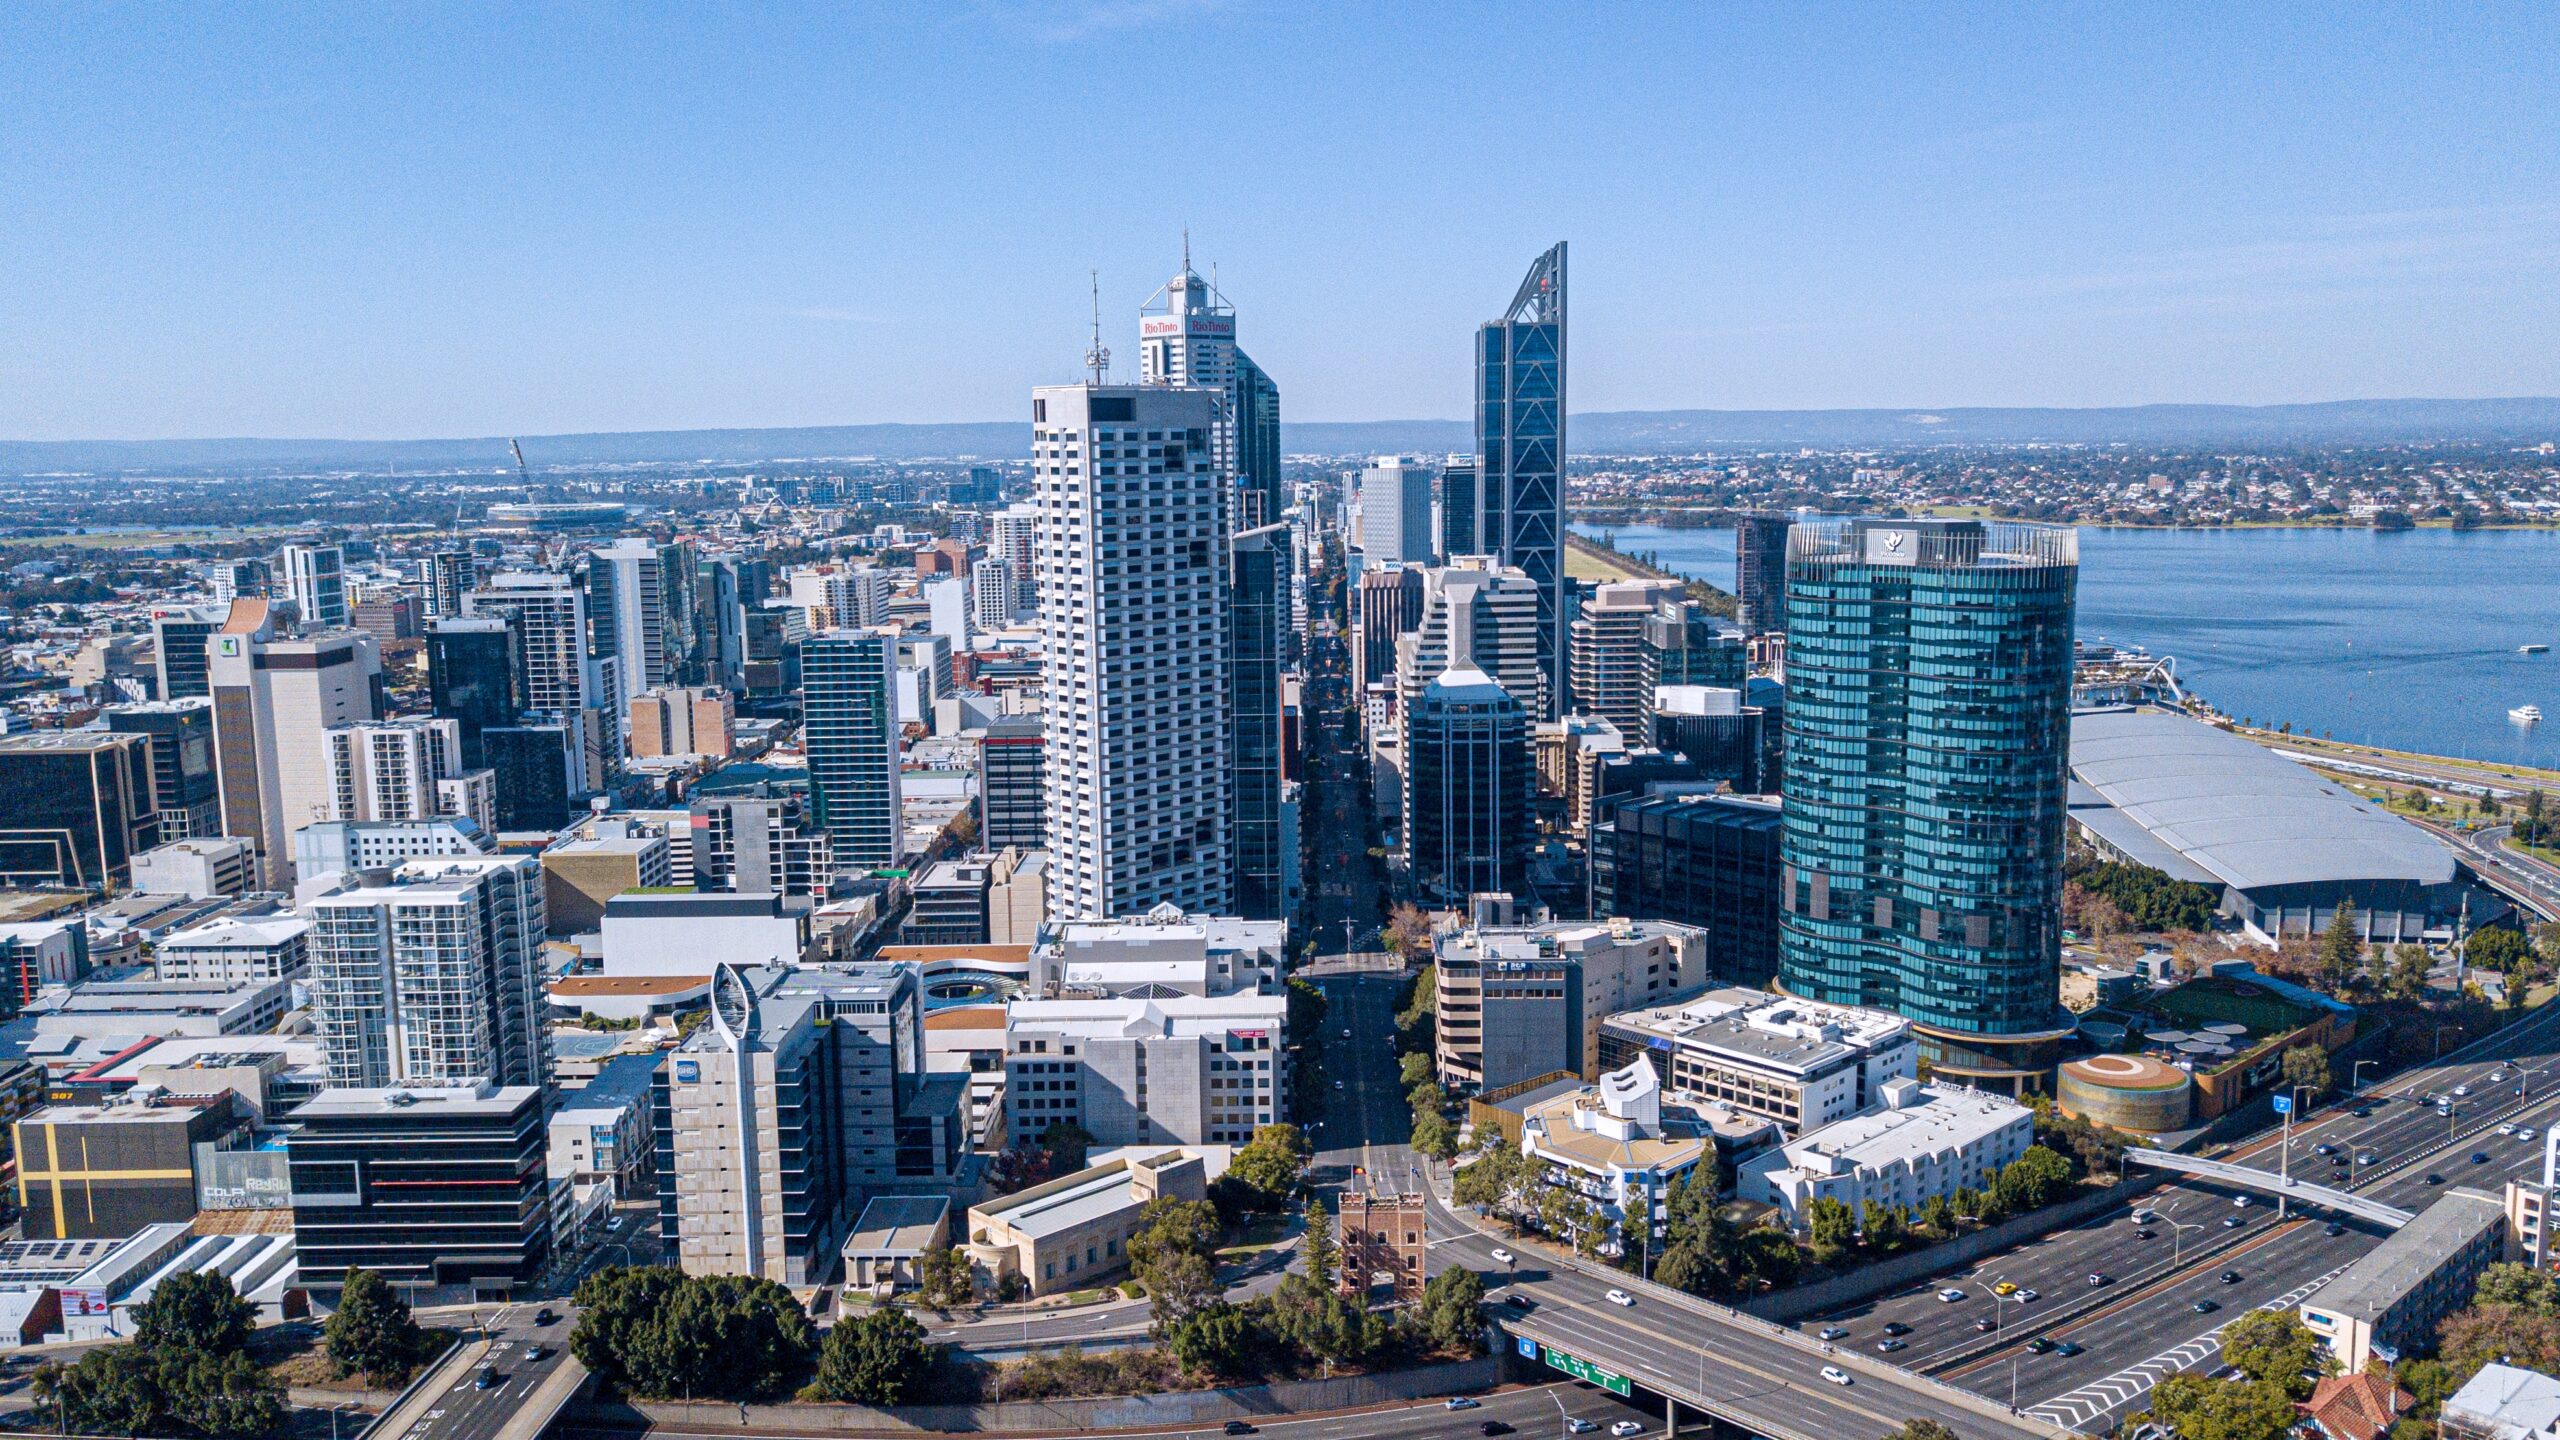
The major CBD Australian office markets are oversupplied, with double-digit vacancy rates that should be suppressing rental growth. However, historically high incentives are boosting the financial appeal for tenants to move into better quality space when their leases expire, even as stated rents rise in many locations.
Related Services Australia Macro Service Defunct In-depth insights and analysis of key domestic and global trends, enabling clients to make better strategic decisions, manage risks and take advantage of newly-developing opportunities in a fast-changing economic environment. Find Out More → Global Macro Strategy Service Global insight and opportunity at your fingertips. Find Out More →
Australia’s rental market tightened considerably in 2022 with rents growing 13.4% y/y nationally. Momentum has continued in 2023, with an increased volume of tenants competing for a relatively static level of supply, contributing to historically low vacancy rates. Moreover, higher interest rates have significantly lifted the mortgage costs for landlords, who are keen to balance their cash flow through higher rental incomings.