

The failures of Silvergate Capital and Silicon Valley Bank have not changed our baseline forecasts for GDP growth, inflation, or policy rates.
 Saarah Ghazi
The failures of Silvergate Capital and Silicon Valley Bank have not changed our baseline forecasts for GDP growth, inflation, or policy rates.
Travel & Tourism accounted for 8% of global greenhouse gas emissions in 2019. Within Travel & Tourism, the lodging industry represents 6% of the total carbon footprint of global tourism.
We think the collapse of Silicon Valley Bank (SVB) will be contained and is not a sign of systemic risks to the banking sector. However, with the US economy likely heading for recession we reiterate our underweight positions on risk assets.
Last week’s liquidation of Silvergate Capital and the collapse of Silicon Valley Bank (SVB) have raised questions about the risks of financial instability to the economy.
Our modelling finds few scenarios in which corporate credit offers a compelling return. Stickier inflation or a sharp sell-off in stocks could lead to credit spreads blowing out again.
In sizing the macro impact of recent US semiconductor export controls on China, we estimate a near-term drag of around 5bps from 2023 GDP levels. Over the medium term (2024-2026), the impact of controls rises to up to a cumulative 0.8% hit to GDP levels.
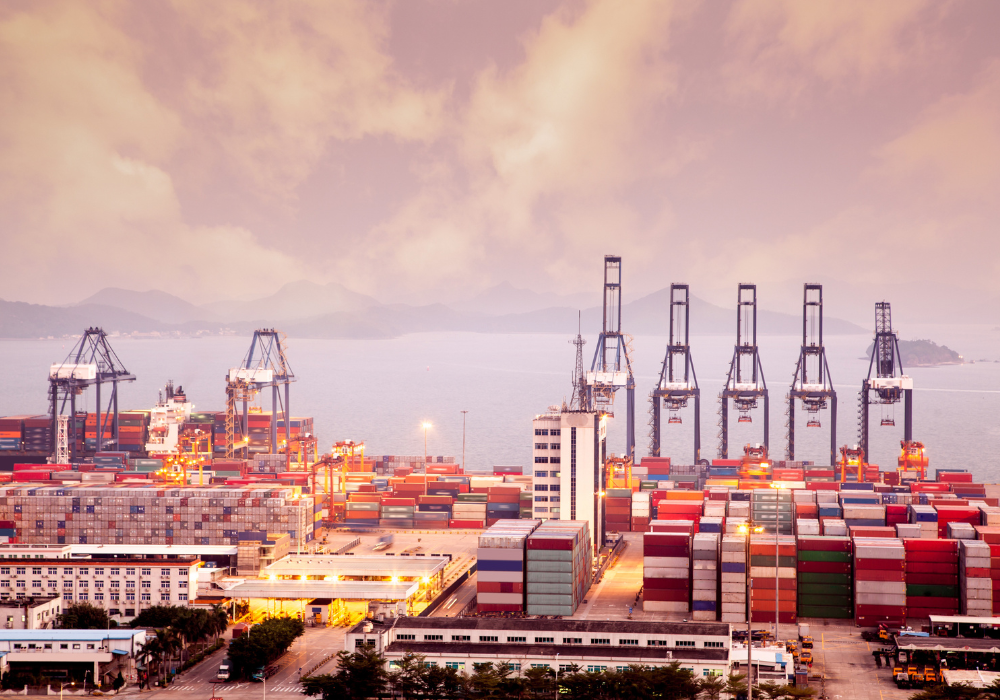
Global electric vehicle (EV) trade has grown undeterred in the last five years—increasing at a compound annual growth rate (CAGR) of 50.4% between 2017-2021—as multiple nations and regions encouraged EV adoption as means for meeting long-term climate change targets.
Japan’s structural labour shortage has deepened. While it may not result in a wage-inflation spiral now, labour scarcity will put upward pressure on wages and inflation in the coming years.
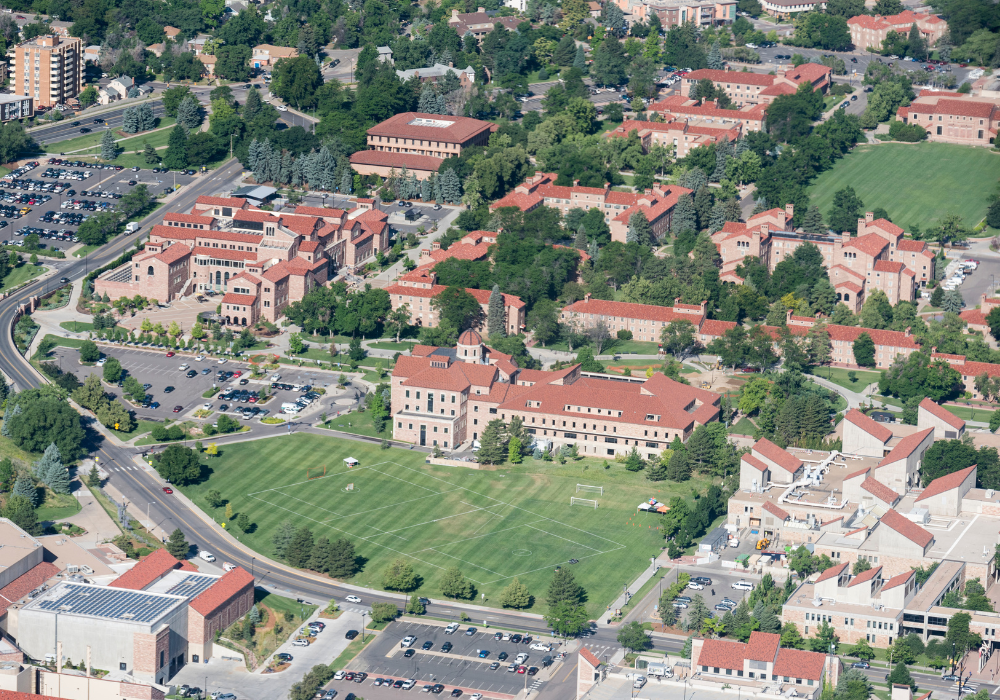
Metros labeled as “college towns” have consistently seen steadier yet often lower job growth than the US average over the last 15 years.
The impact of policies to address climate change cannot be discussed only in national terms. There will be variations by region. Cities overall are likely to retain or increase their growth premia over national economies, but some will suffer.
The Bank of Japan enhanced its funds-supplying operations in January, after widening the tolerance band for 10-year JGB yields in December.
Our 2023 growth forecast of 4.5% for China is still 6-tenths below the consensus’ 5.1%, owing to a more cautious view on net exports and private consumption. It is also much lower than the five-year average pre-pandemic growth pace of 6.7%.
The incoming data likely warrant some adjustments to the baseline forecast, particularly for the path of the target range for the fed funds rate.
A cautious 2023 budget amid the need to stabilize government finances post pandemic means that fiscal policy won’t be able to counter restrictive monetary policy in supporting a slowing economy this year.
As the world population approaches 8 billion, over a quarter belong to Generation Z (those born between 1997 and 2012). Whilst their impact to both the economy and society is currently limited by their youth, this massive cohort is now joining the workforce.
Cities are the primary centres for driving economic growth around the world. Today, the urban economic landscape is dominated by advanced city economies like New York, Tokyo, and London.
Our indicators suggest global economic sentiment is improving despite the impact of higher interest rates, geopolitical uncertainty, and the squeeze on real incomes.
Housing affordability deteriorated in 2022 by the most since the housing crisis and rebalancing is needed to foment healthier market dynamics. But supportive structural factors mean a major correction in house prices is unlikely, in our view.
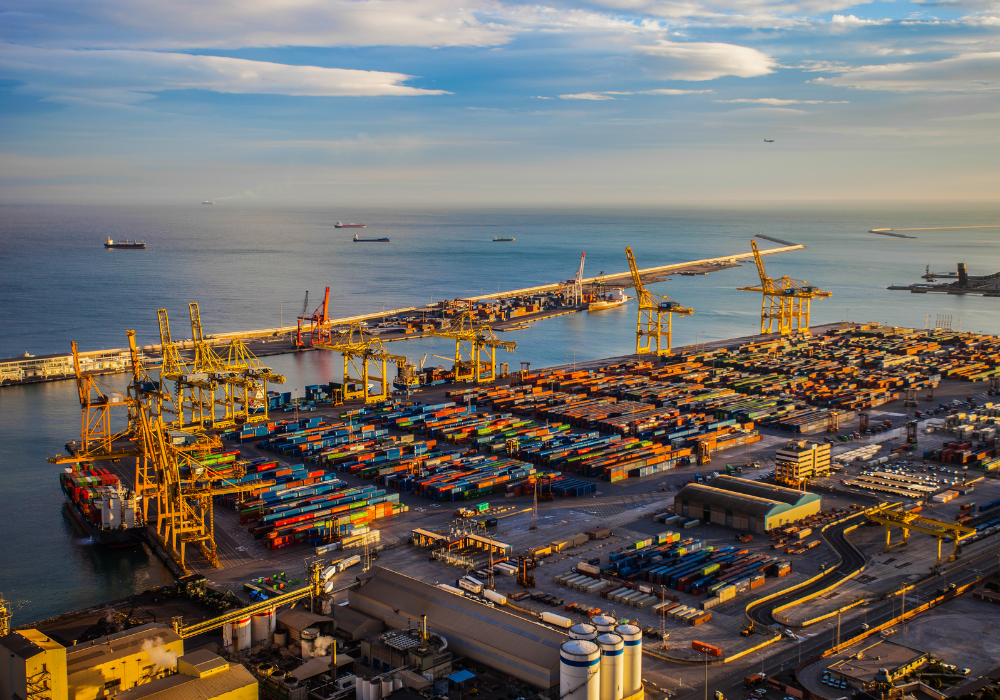
Supply chain stress fell at the beginning of the year and further easing is likely due to weaker domestic and global demand.
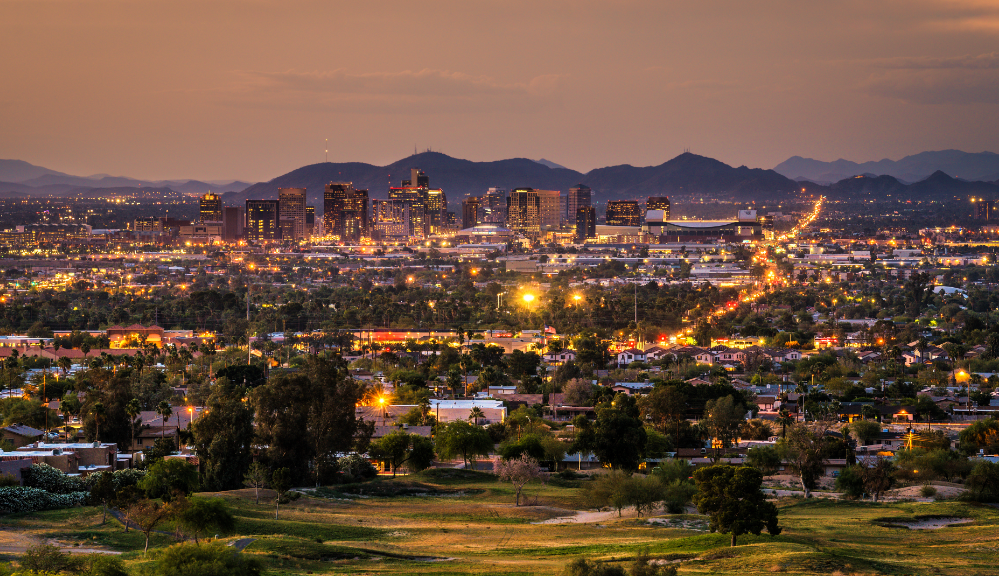
Although it still faces promising growth from the continued investment in new semiconductor facilities, Phoenix growth slowed somewhat in 2022.