OE Logo

The removal of most of Canada’s retalliatory tariffs and a continuing low US effective tariff rate improves growth prospects. Yet, the Canadian economy will remain on the verge of a recession and uncertainty will remain high until renegotiation of the USMCA.
In our recent Made in America research series, we explored key trends at a macro, sectoral and regional level as to the potential for US reshoring, and what it means for business and policy makers. Join the authors of the series as they discuss their findings and key conclusions for US manufacturing over the next decade.

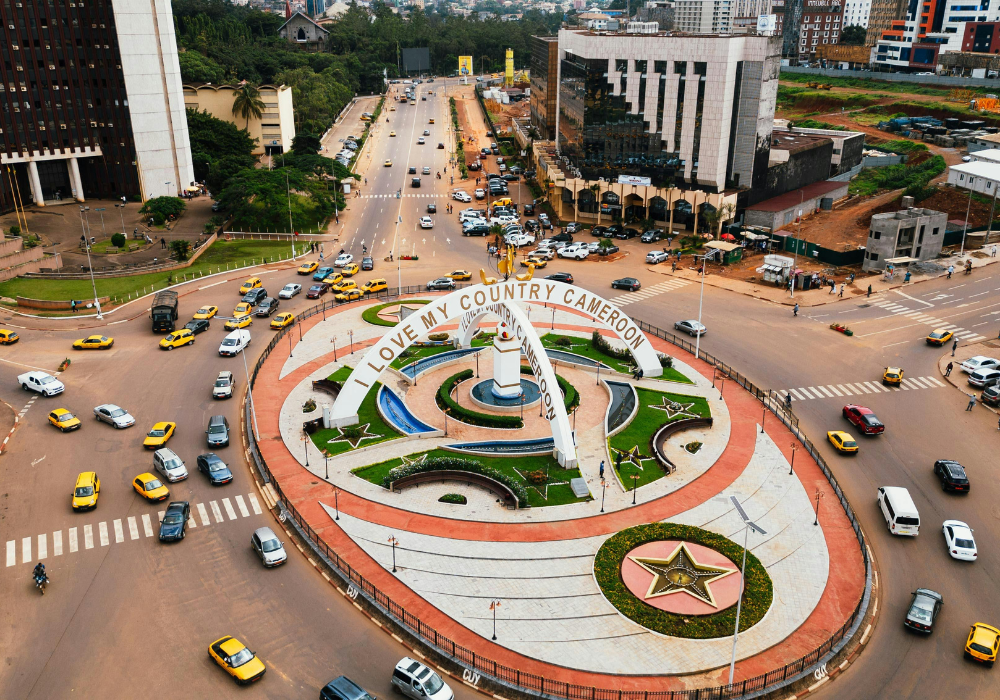
President Paul Biya, the world’s oldest head of state at 92, is set to win an eighth term in office in the October 12 presidential election and to rule until he passes away. The interesting question now becomes what the post-Biya transition will look like.

Nordics flags

Webinar Nordics: Steady growth despite new trade barriers

Eurozone flag

In this instalment of our Eurozone research webinar series, we will present our recent research on fiscal positions of various countries in the Eurozone and our assessment of the macroeconomic impact of the various fiscal policy packages, including the ongoing European defence spending drive to meet the new NATO spending targets.

US FOMC minutes economy

Risks are swirling around the economy and this has caused the Federal Open Market Committee to become divided about the course of monetary policy next year. Angst about the labor market are being prioritized by the Fed over inflation, for now. Monetary policy is a blunt instrument and it can’t address less labor supply that could be amplified by recent policy changes. Downside risks to labor market have become more threatening as the pass-through to consumer prices from tariffs is likely to intensify. On the upside, the economy will continue to reap the benefits of AI-related investment that shows no sign of slowing down.

5G and AI industry

Join Oxford Economics to uncover the opportunities and risks shaping global technology investment in 2025. We’ll explore:
• What threats could derail enterprise tech spending?
• Which markets and industries are best placed to drive growth?
• How will AI and cloud adoption reshape strategies for the year ahead?

he UK economy remains exceptionally fragile; subdued growth, high inflation, and a weak fiscal position are set to persist, and a sustainable driver of UK growth has yet to emerge. The Budget on November 26 could add to the headwinds, with further substantial tightening of fiscal policy likely. In this panel discussion, Andrew Goodwin, Michael Saunders, and Liam Sides will discuss the causes of the UK’s macroeconomic and regional problems and assess whether the government has the solutions.

Expert insight at your fingertips

We will explore the key economic drivers beyond GDP, including private consumption, inflation, earnings, and disposable income, among others, and explain why they matter for consumer markets. The session will also cover common challenges such as irregular periods and limited data histories, and share anonymised case studies showing how these can be addressed while balancing statistical accuracy with economic logic.

Commercial real estate performance

We’re excited to announce the launch of US city-level forecasts covering key performance metrics across 42 US markets and major property sectors. In this elevated long-term bond yield environment, city and sector analysis will be crucial for maximizing commercial real estate (CRE) investment/portfolio performance. In this webinar we will provide an overview of our near-term national commercial real estate (CRE) capital market expectations and highlight key market-level trends from our new product.