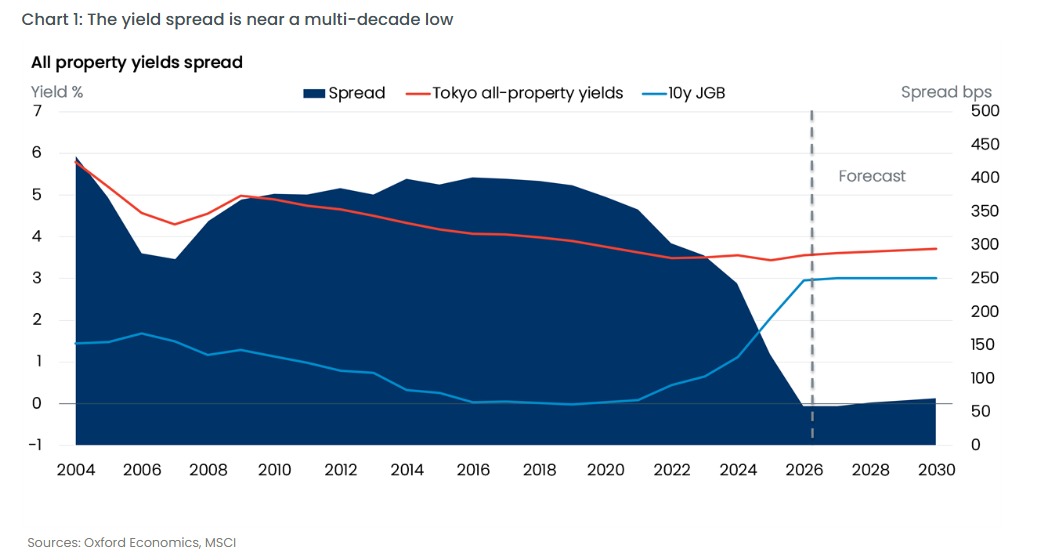
Japan’s CRE yield spread vanishes after recent bond moves
The recent rise in interest rates is challenging Japan’s real estate investment. We expect the Bank of Japan to raise its policy rate to 1.75% by April 2027, while the 10-year Japanese government bond (JGB) yield has risen to around 3%, its highest in three decades, signalling firmer inflation expectations.
Yield spreads have sharply narrowed because property cap rates haven’t widened to compensate. The prime Tokyo office spread over the 10-year JGB is now only around 10bps-15bps, down from roughly 140bps in our January note and more than 300bps in 2022.
Underwriting assumptions will need to allow for higher exit cap rates as discount rates and funding costs pose greater downside risks. We forecast steady yield expansion over the next five years for Tokyo all property, but positive occupier fundamentals should offset some of this impact to support total returns.
In this environment, investors should focus on sectors where income growth is supported by genuinely tight market conditions. Japan still offers attractive opportunities, but selectivity is becoming increasingly important as financing costs rise..