
Research Briefing
| Aug 2, 2024
How our FX risk tool helps predict exchange rate sell-offs
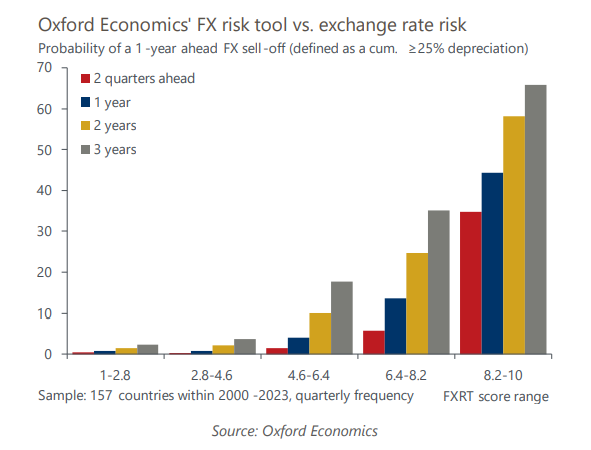
The latest revamp of our foreign exchange risk tool (FXRT) demonstrates the enhanced predictive power of selected vulnerability metrics over future exchange rate movements. Our newly updated weights show that scores explain around 40% to 60% of y/y nominal bilateral exchange rate movements in a panel of 157 currencies from 2000 to Q1 2024.
What you will learn:
- On a global level, the FXRT scores help highlight the currencies most susceptible to extreme FX movements. Our backtests show that nearly two-thirds of currencies within the riskier score range experienced a 25% or higher sell-off within the next three years.
- We find that conditional distribution skews pair well across scores. Riskier currencies according to the FXRT tend to have more prominent negative skews, consistent with the view that once fundamental vulnerabilities are exposed, negative sentiment becomes amplified. The revisions suggest increases in the FX risk for the Japanese yen and the Swedish krona.
- Our risk scores are useful to inform policy or financial market strategy decision-making. They are also beneficial quantitative inputs to inform other in-depth analyses in the context of econometric models focussed on exchange rate research.
Related Reports
Click here to subscribe to our asset management newsletter and get reports delivered directly to your mailbox
Why bond yields and term premia are likely to remain high
Term premia are now back to their mid-2000s levels – high compared to the last 10 years.
Read more: Why bond yields and term premia are likely to remain high
How will central banks react to higher bond yields?
We expect major central banks will continue to tighten in coming months.
Read more: How will central banks react to higher bond yields?
Bonds and the end of the global savings glut
Is the “end of the global savings glut” story reflected in bond prices? Three different approaches to fair value for 10-year Treasurys suggest the answer is yes.
Read more: Bonds and the end of the global savings glut
Economics for Asset Managers
Read more of our analysis and reports on asset management and economic outlook.
Read more: Economics for Asset Managers